By Virtual Cost Segregation
The best cost segregation study provider for rental property investors
 Built to IRS standards
 Audit support includedFlat price for every study3 to 5 business days
Professional landscaping on a residential rental usually depreciates as 15-year land improvement property in a cost segregation study, not as part of the 27.5-year building and not as nondepreciable land. The exact treatment depends on how the landscaping functions, whether the study documents it as a discrete asset, and when it was placed in service relative to the 2026 bonus depreciation rules.
- Professional landscaping typically depreciates as 15-year land improvement property, separate from the building and the raw land.
- Sod, plantings, irrigation, and hardscape can qualify for 100% bonus depreciation in 2026 if acquired and placed in service after January 19, 2025.
- Grading, clearing, and site prep tied directly to the parcel usually stay nondepreciable, just like the land itself.
- A cost segregation study documents landscaping as its own line item instead of leaving it buried inside a blended building rate.
- Classification depends on function and documentation, not on the fact that landscaping looks nice.
Why This Matters for Rental Owners
Most landlords write a single check to a landscaping company and never think about it again come tax time. That check often buys several categories of property with different depreciation treatments, and lumping it all into the building's 27.5-year schedule leaves real deductions on the table.
A study that separates land improvements after cost segregation from the building shell and from the land parcel gives you a faster write-off on the pieces that qualify. For an owner in the 37% tax bracket, moving a few thousand dollars of landscaping from a 27.5-year schedule to a 15-year schedule with bonus depreciation changes the timing of real cash back in 2026.
How Professional Landscaping Is Classified in a Rental Property Cost Segregation Study
Engineers reviewing a residential rental separate landscaping into functional categories, because the tax code treats each one differently. The table below reflects typical treatment based on IRS guidance on land improvements; your actual result depends on your property's documentation and facts.
| Landscaping element | Typical classification | Recovery period | Bonus eligible (2026)* |
|---|---|---|---|
| Sod, shrubs, ornamental trees | Land improvement | 15 years | Yes, if separately documented |
| Irrigation system | Land improvement | 15 years | Yes, if separately documented |
| Retaining walls, walkways, patios | Land improvement | 15 years | Yes, if separately documented |
| Mulch beds, edging, decorative gravel | Land improvement | 15 years | Yes, if separately documented |
| Grading, clearing, drainage tied to the parcel | Land | Not depreciable | No |
*Assumes the asset was acquired and placed in service after January 19, 2025, under the One Big Beautiful Bill Act's restored 100% bonus depreciation.
Sod, Shrubs, and Plantings: 15-Year Land Improvement Property
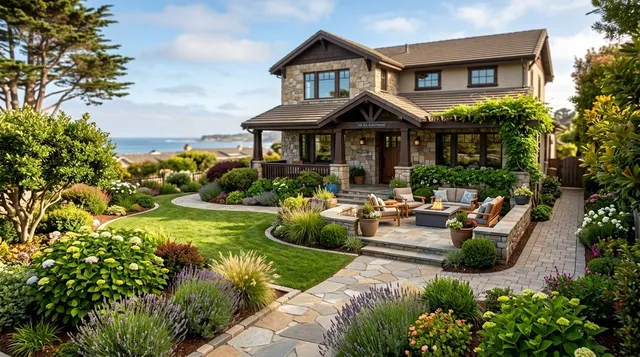
Sod, shrubs, and ornamental trees installed as part of a professional landscaping job generally classify as 15-year land improvement property rather than 27.5-year residential property. That's a 12.5-year acceleration on the same dollars, assuming the study documents the plantings as a distinct asset separate from the land under it.
The distinction matters because the IRS treats plants and turf as improvements to the land, not as the land itself. Land has no depreciable life at all, so keeping plantings misclassified as "land" instead of "land improvement" costs you the deduction entirely.
Irrigation Systems: 15-Year Land Improvement Property
Sprinkler heads, drip lines, and irrigation controllers installed to support landscaping generally fall into the same 15-year land improvement bucket. These systems function separately from the building's plumbing, which supports a shorter recovery period than the structure itself.
Retaining Walls and Hardscape: 15-Year Land Improvement Property
Walkways, patios, and retaining walls tied to landscaping design typically classify as 15-year land improvements when they serve a decorative or site-access function rather than supporting the building's structure. A retaining wall that holds back a hillside to protect the foundation can get scrutinized differently than a decorative wall bordering a flower bed, so documentation of purpose matters.
Grading and Site Prep: Not Depreciable
Grading, clearing, and drainage work performed to shape the parcel itself generally stays nondepreciable, the same as the raw land. This is the category most owners assume is deductible and isn't. If your landscaping invoice bundles $3,000 of grading with $8,000 of plantings and hardscape, only the second figure has a shot at a depreciation schedule.
Why Landscaping Classification Varies
A handful of factors push the same landscaping line item toward different outcomes on two different properties:
- Function: decorative plantings and hardscape versus structural grading tied to the building's foundation
- Documentation: whether the invoice breaks out plant material, irrigation, and hardscape separately, or bundles everything as one lump sum
- Timing: whether the landscaping went in with original construction, during a renovation, or as a standalone project
- Placed-in-service date: assets acquired and placed in service after January 19, 2025 qualify for 100% bonus depreciation in 2026 under current law; earlier dates follow different phase-out percentages
- Repair versus capital improvement: replacing dead sod is a repair you deduct now, while installing an entirely new landscape design is a capital improvement you depreciate
- Whether it's original to the single-family rental or added to a property you've owned for years
Land Value vs. Improvement Value on Your Tax Bill
The IRS split between land and land improvements isn't the only place this distinction shows up. County assessors run a parallel exercise every year, dividing your property's assessed value between land and improvements to calculate your property tax bill, and that split doesn't always track reality.
An assessor who overweights your land value relative to your actual improvements inflates your tax bill independent of anything your cost segregation study finds. Owners who suspect their land-to-improvement ratio is off often turn to property tax protest companies to challenge that local valuation, which is a separate process from the federal depreciation split a cost segregation study produces but runs on the same underlying logic: land and improvements are not the same asset.
Bonus Depreciation on Landscaping in 2026
Land improvements with a recovery period of 20 years or less, including qualifying landscaping, get 100% bonus depreciation for property acquired and placed in service after January 19, 2025 under the One Big Beautiful Bill Act. That means the full reclassified value of your sod, irrigation, and hardscape can potentially hit your 2026 return in year one instead of trickling out over 15 years.
A property purchased for $500,000 with a study reclassifying 25% of value into shorter-lived categories moves roughly $125,000 into 5-, 7-, and 15-year buckets. Landscaping and other land improvements typically make up a slice of that figure, not the whole thing, alongside cabinetry, flooring, and site-specific electrical work.
Does Landscaping Qualify for Bonus Depreciation in 2026?
Landscaping classified as a 15-year land improvement qualifies for 100% bonus depreciation in 2026 when it's placed in service after January 19, 2025 and documented as a distinct asset from the land and building. Grading and site clearing tied to the parcel itself don't qualify because they're treated as land, which has no depreciable life at all.
Is Landscaping a Repair or a Capital Improvement?
Landscaping is a repair when you're replacing dead plants or refreshing mulch, and a capital improvement when you're installing a new design, irrigation system, or hardscape that adds value beyond restoring the prior condition. Repairs get deducted in the year you pay for them; capital improvements get depreciated, which is where a cost segregation study comes in.
Can You Cost Segregate Landscaping on a Property You Already Own?
Yes, a cost segregation study can identify and reclassify landscaping on a property you've held for years through a look-back study and Form 3115 accounting method change, without amending prior returns. This catches up missed depreciation in the current tax year rather than requiring you to refile past ones.
A Virtual Cost Segregation report runs a flat $2,200 fee and documents landscaping, irrigation, and hardscape as separate asset classes with photos and cost detail your CPA can defend if the IRS asks questions. That documentation is the difference between a defensible 15-year classification and an assumption an examiner can knock back to 27.5 years.
Get Your Landscaping Reclassified
Flat-fee, engineering-based study documented for audit defense.
FAQ
How do you depreciate professional landscaping on a rental property?
Professional landscaping on a rental property typically depreciates as 15-year land improvement property once a cost segregation study separates it from the building and the land. Sod, irrigation, and hardscape usually qualify; grading and site clearing tied to the parcel don't.
Is landscaping part of the 27.5-year residential building?
No, landscaping is generally not part of the 27.5-year building; it's classified as a separate 15-year land improvement in a cost segregation study. Keeping it inside the building schedule means depreciating it 12.5 years slower than necessary.
Does landscaping qualify for 100% bonus depreciation in 2026?
Landscaping classified as a 15-year land improvement qualifies for 100% bonus depreciation in 2026 when placed in service after January 19, 2025 under the One Big Beautiful Bill Act. Documentation showing it's a discrete asset separate from the land is required.
What landscaping costs are never depreciable?
Grading, clearing, and drainage work performed on the raw parcel itself are never depreciable because they're treated as land, which has no recovery period. Only improvements added to the land, like plantings and irrigation, carry a depreciation schedule.
Can landscaping be reclassified on a property I already own?
Yes, a look-back cost segregation study combined with Form 3115 can reclassify landscaping on a property you've held for years and catch up missed depreciation in the current year. You don't need to amend prior tax returns to do this.
How much does a cost segregation study cost for a rental with landscaping?
A flat-fee residential cost segregation study runs around $2,200 regardless of how many asset categories, including landscaping, get documented. That's a fixed cost against a potential five-figure acceleration in deductions.
Is landscaping a repair or a capital improvement for tax purposes?
Landscaping is a repair when you're replacing dead plants or refreshing existing beds, and a capital improvement when you're installing a new design or irrigation system that adds value. Repairs deduct immediately; capital improvements depreciate over time.
One Last Thing
Most landlords assume their landscaping invoice is either fully deductible or fully buried in the building basis, and both assumptions cost money. The invoice usually splits three ways: a repair piece you deduct now, a 15-year land improvement piece eligible for 100% bonus depreciation in 2026, and a land-grading piece that never depreciates at all. Ask your landscaper for an itemized invoice before the project closes out; it makes the classification cleaner and the study faster.