By Virtual Cost Segregation
The best cost segregation study provider for rental property investors
 Built to IRS standards
 Audit support includedFlat price for every study3 to 5 business days
Outdoor lighting and fencing on a rental property are typically classified as land improvements, not building components, which places them in the 15-year MACRS recovery period instead of the 27.5-year residential rental schedule. That reclassification is what makes many of these assets eligible for bonus depreciation, currently restored to 100% for property acquired and placed in service after January 19, 2025 under the One Big Beautiful Bill Act (OBBBA). The actual treatment depends on how each fixture is attached, what function it serves, and how well it's documented in the engineering-based study, so no fixture type automatically qualifies for a shorter recovery period without that supporting analysis.
- Fencing and most freestanding outdoor lighting are typically classified as 15-year land improvements, not 27.5-year residential rental property.
- That reclassification is what opens the door to 100% bonus depreciation under OBBBA for property acquired and placed in service after January 19, 2025.
- An engineering-based cost segregation study documents attachment method and function for each asset instead of assuming a blanket treatment.
- Building-mounted lighting wired into the structure's electrical system is usually treated differently than freestanding landscape fixtures.
Why This Matters for Short-Term and Long-Term Rental Owners
A fence around a vacation rental or landscape lighting along a driveway rarely shows up as a separate line item on a settlement statement. It gets buried in the purchase price or the renovation invoice, then depreciated over 27.5 years by default because that's the standard schedule for residential rental buildings.
An engineering-based cost segregation study pulls those costs back out and evaluates each one against IRS classification standards under Section 1250 and the land improvement rules. For a short-term rental owner using the STR loophole to offset W-2 income, moving a fence or a set of landscape fixtures from a 27.5-year schedule to a 15-year one with 100% bonus depreciation in 2026 can mean the difference between a deduction realized decades from now and one realized this tax year.
How Are Outdoor Lighting and Fencing Classified in a Rental Cost Segregation Study?
Classification comes down to three questions for every fixture: is it attached to the building or to the land, does it serve a structural or building-system function, and is it removable without damaging the structure. Here's how these two categories typically shake out.
| Asset | Typical Classification | Recovery Period | Bonus Depreciation Eligible? |
|---|---|---|---|
| Freestanding perimeter or privacy fencing | Land improvement | 15-year | Yes, if placed in service after Jan 19, 2025 |
| Landscape or pathway lighting (freestanding) | Land improvement | 15-year | Yes |
| Building-mounted exterior lighting wired into house electrical | Building component | 27.5-year | Generally no |
| Removable string lighting or portable amenity fixtures | Personal property | 5-year | Yes |
| Security or access-control fencing/gates | Land improvement | 15-year | Yes |
This table is a starting point, not a determination. A study documents each asset individually rather than applying one row to every fixture on the property.
Fencing: Typically a 15-Year Land Improvement
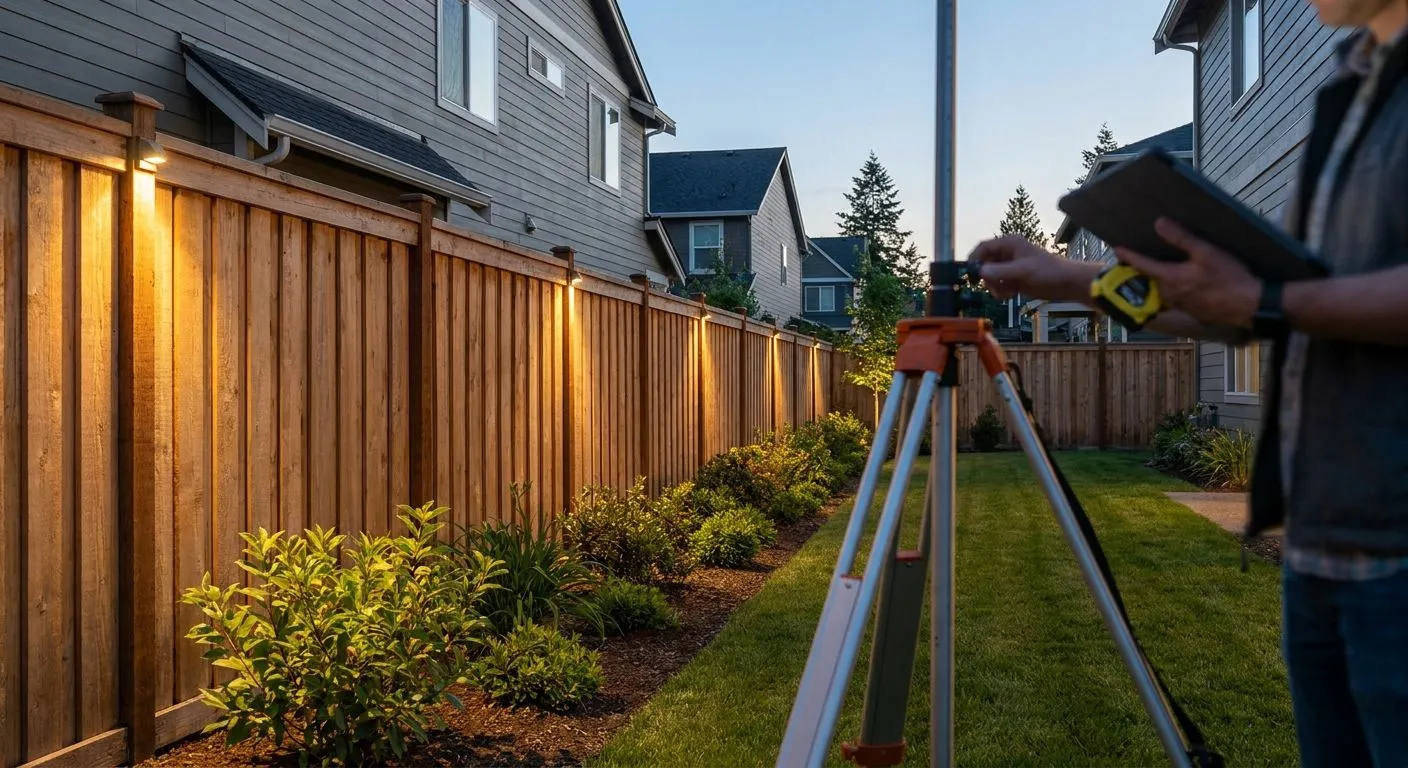
Most fencing on a residential rental, whether it's a privacy fence around a hot tub, a pool enclosure required for safety, or a perimeter fence marking the lot line, functions as a land improvement rather than part of the building. It sits on the land, serves the land, and can generally be removed or replaced without altering the structure itself.
That classification puts standard fencing on the 15-year MACRS schedule, which under 2026 depreciation rules for property acquired and placed in service after January 19, 2025 is eligible for 100% bonus depreciation. The exception is fencing that's structurally integrated into the building, such as a retaining wall that also functions as a foundation wall, where classification depends on engineering facts specific to that installation.
Outdoor Lighting: Split Between Land Improvement and Personal Property
Outdoor lighting doesn't classify as cleanly as fencing because it spans a wider range of installation types. Landscape lighting staked into the yard, solar path lights, and freestanding post lamps typically land in the same 15-year land improvement bucket as fencing.
Removable or seasonal lighting used as a short-term rental amenity, string lights on a patio pergola or portable spotlights for a firepit area, can sometimes be treated as personal property with a 5-year recovery period, which also carries 100% bonus depreciation eligibility in 2026. Lighting hardwired into the building's electrical panel and mounted to the exterior wall or roofline is more often treated as a building component on the 27.5-year schedule, because it's functionally part of the structure's electrical system rather than a separate land asset.
Why Classification Varies From Property to Property
No two rental properties get the identical treatment for outdoor lighting and fencing, even when the fixtures look similar on the surface. A few factors drive most of the variation:
- Attachment method. Bolted or wired into the structure versus freestanding or staked into the ground changes whether an asset is a building component or a land improvement.
- Function. A fence that's purely decorative is treated differently in practice than one required for pool safety compliance or one that doubles as a retaining structure.
- Placed-in-service date. Bonus depreciation eligibility depends on when the asset went into service, not just what it is; assets acquired and placed in service after January 19, 2025 qualify for the restored 100% rate under OBBBA.
- Documentation quality. A study that identifies each fixture with cost detail and photographic support holds up better under IRS audit review than a blanket percentage applied to "site improvements."
- Renovation versus original construction. Fencing and lighting added during a renovation may carry different cost documentation than items included in the original purchase price, which affects how cleanly they can be identified as short-life assets.
- Short-term rental amenity use. Owners running an Airbnb or VRBO often add lighting and fencing specifically to enhance the guest experience, which can support personal property treatment if the item is genuinely removable and not integral to the structure.
An engineering-based study from Virtual Cost Segregation walks through each of these factors fixture by fixture instead of applying a flat assumption to every outdoor asset on the property. That's the difference between a report that survives IRS scrutiny and one that gets flagged for using rule-of-thumb percentages.
Does a New Fence Installed on a Rental Property Qualify for Bonus Depreciation?
A new fence typically qualifies for 100% bonus depreciation in 2026 if it's classified as a land improvement with a 15-year recovery period and was placed in service after January 19, 2025. Fencing installed before that date under the prior phase-down schedule may fall under a lower bonus percentage, so the placed-in-service date matters as much as the fence itself.
Is Outdoor Lighting a 5-Year or 15-Year Asset?
Outdoor lighting can fall into either category depending on how it's installed. Freestanding landscape lighting typically sits at 15 years as a land improvement, while removable, portable fixtures used as rental amenities can sometimes qualify as 5-year personal property, and both classifications are eligible for 100% bonus depreciation in 2026 when the asset is properly documented.
Can Existing Fencing Be Reclassified After the Fact?
Existing fencing already in service can sometimes be reclassified through a look-back study and a Form 3115 accounting method change, which lets an owner catch up missed depreciation without amending prior returns. Whether that catch-up applies depends on how long the asset has been in service and how the original cost was documented, which a CPA and cost segregation provider typically review together before filing.
FAQ
Is fencing a 15-year or 27.5-year asset on a rental property?
Fencing is typically a 15-year land improvement rather than a 27.5-year building component, since it serves the land and not the structure itself. Fencing structurally tied to the building, like a retaining wall doubling as a foundation wall, may be treated differently based on the specific installation.
Does outdoor lighting qualify for bonus depreciation in 2026?
Outdoor lighting classified as a land improvement or personal property qualifies for 100% bonus depreciation in 2026 when acquired and placed in service after January 19, 2025 under OBBBA. Lighting wired into the building's electrical system as a fixed component is generally excluded from that treatment.
How much of a rental property's cost is typically reclassified in a cost segregation study?
Cost segregation studies typically reclassify 20-45% of a property's cost basis into shorter recovery periods, depending on the property type and its finishes. Outdoor lighting and fencing are usually a small piece of that total, alongside larger categories like flooring, cabinetry, and site improvements.
Does a swimming pool fence get the same treatment as a regular perimeter fence?
A pool safety fence is typically treated the same as other freestanding fencing, as a 15-year land improvement, though it's often documented alongside the pool itself in a study. Review how a [pool is classified](https://virtualcostsegregation.com/blog/how-to-depreciate-a-swimming-pool-in-a-cost-segregation-study/) since the two assets are frequently installed together.
Can DIY fencing or lighting installations still be included in a cost segregation study?
DIY installations can be included if the cost is documented with receipts, invoices, or contractor estimates tied to the specific work performed. Without documentation, an engineering-based study has less to work from, which can reduce the reclassified amount for that item.
Is a security gate treated the same as a fence for depreciation purposes?
A security or access-control gate typically follows the same land improvement classification as fencing, landing on the 15-year schedule. Electronic components of the gate system, like keypads or motors, may be evaluated separately depending on their function.
Do I need a site visit for outdoor lighting and fencing to be classified correctly?
A site visit is not required for most residential rental studies; photo documentation, invoices, and property records are usually enough for an engineering-based study to classify outdoor assets. Review how a [no-site-visit study maintains accuracy](https://virtualcostsegregation.com/blog/no-site-visit-cost-segregation-accuracy/) for details on what documentation is used instead.
What happens if outdoor lighting or fencing is misclassified in a study?
Misclassification can trigger an IRS challenge during an audit, since land improvements and personal property are held to different documentation standards than building components. A conservative, well-documented classification for each fixture is what keeps a study audit-defensible.
One Last Thing
Most owners assume fencing and lighting are too minor to matter next to a roof or an HVAC system, but on a smaller rental under a few hundred thousand dollars, these site improvements can represent a meaningful share of the reclassified total simply because they're 100% bonus-eligible in 2026 while larger structural components sometimes aren't. Don't let a study lump these into a generic "site improvements" line without individual documentation. That's the detail that separates a report an IRS examiner accepts from one that gets a second look.
See what your property could reclassify
Get a free savings estimate before ordering a full study.