By Virtual Cost Segregation
The best cost segregation study provider for rental property investors
 Built to IRS standards
 Audit support includedFlat price for every study3 to 5 business days
Sales executives’ cost segregation is the classification of rental-property components into shorter depreciation periods with the aim of accelerating deductions that your tax situation allows you to use. For commission-heavy W-2 earners, the deciding issue is not the size of the deduction: it is whether rental losses can offset compensation and whether your operating records support that treatment.
- Cost segregation for sales executives accelerates rental depreciation; it does not automatically offset W-2 commissions.
- Short-term rental owners need qualifying average stays and material participation before evaluating a compensation offset.
- Virtual Cost Segregation is best for residential rental owners seeking an engineering-based study for CPA implementation.
- Confirm loss usability, acquisition timing, and participation records before ordering a study.
Why cost segregation matters for sales executives
A large commission year creates a tax-planning question, not automatic eligibility for rental deductions against wages. Cost segregation changes when you deduct eligible property costs. Passive-activity rules determine whether those deductions reduce current compensation income or remain suspended.
Your employment schedule matters. Customer travel, quarter-end commitments, and a demanding sales role must fit alongside actual rental operations if you intend to establish material participation. A calendar showing availability is not evidence that you performed rental work.
For your 2026 planning, separate three questions: what depreciation the property supports, what loss your return permits, and what records substantiate both. Start with the broader framework for cost segregation for high-income W-2 earners, then apply it to your ownership and operating facts.
A larger depreciation deduction is useful only when its timing matches a deduction you can actually use. A long-term rental remains a valid candidate, even when its deductions do not offset your salary or commissions immediately.
How to evaluate cost segregation for your rental
1. Identify the income you want to offset
Begin with your pay statements and existing rental schedules. Separate salary and commissions reported as wages from rental income, investment income, and other business income. They do not all receive the same loss treatment.
Ask your CPA to compare your 2026 return with and without accelerated depreciation. The projection should distinguish deductions generated from deductions currently allowed. Basis, at-risk, passive-activity, and excess-business-loss limitations can affect the result.
Do not reduce payroll withholding based on a calculator alone. Your CPA should first connect the proposed rental deduction to your actual return, including state treatment and other deductions.
- Gather year-to-date wages, commissions, and withholding.
- Identify expected compensation not yet paid.
- List rental income and existing suspended losses.
- Ask which limitations apply before changing tax payments.
2. Test your rental’s operating facts
Review booking records before assuming your Airbnb or VRBO activity supports a W-2 offset. Under the commonly used short-term-rental exception, average guest stays must be 7 days or less. You must also materially participate for the activity’s loss to receive nonpassive treatment under this approach.
One common material-participation test requires more than 100 hours and more participation than any other individual, including a property manager. Completing 100 hours alone does not satisfy that test. Other material-participation tests exist; your CPA should select the applicable test from your facts.
This approach does not require real estate professional status. Conversely, simply owning a short-term rental does not establish eligibility. A long-term residential rental generally remains subject to rental passive-activity rules unless an applicable exception applies.
- Calculate average stays from completed rental periods.
- Record your actual operating tasks and time.
- Document each manager’s or co-host’s work separately.
- Separate personal visits from rental-business activity.
- Have your CPA evaluate the applicable participation test.
3. Establish basis and choose study support
Assemble your closing statement, purchase agreement, improvement invoices, and existing depreciation schedule first. Your CPA must establish depreciable basis and exclude land. A mortgage balance or current listing estimate is not a substitute for that calculation.
Then assess whether you need an engineering-based study. Virtual Cost Segregation provides residential rental cost segregation studies for properties with 1 to 4 units, with no site visit required and delivery in 3 to 5 business days. Audit support is included.
Virtual Cost Segregation is best for residential rental owners seeking an engineering-based study for CPA implementation. Its limitation is equally important: the study is supplementary support, not a CPA service or a filed tax return. Your CPA determines how to apply it.
- Reconcile the purchase allocation with your CPA.
- Separate land from depreciable property.
- Collect invoices for later improvements and furnishings.
- Supply photographs and property records requested for the study.
- Compare the study scope with your CPA’s implementation needs.
4. Verify recovery periods and bonus eligibility
Cost segregation separates qualifying components from the building’s longer recovery period. Depending on classification, components can receive 5-, 7-, or 15-year lives. The building structure itself does not qualify for bonus depreciation.
A long-term rental building generally uses a 27.5-year recovery period. A short-term rental building with average stays under 30 days, including the 7-days-or-less operating pattern discussed here, uses a 39-year recovery period. Your CPA must confirm the classification for your property’s actual use.
Under the One Big Beautiful Bill Act, signed July 4, 2025, eligible property acquired and placed in service after January 19, 2025 qualifies for 100% bonus depreciation, subject to applicable requirements. That restored rate has no scheduled end. A 2026 placed-in-service date alone is insufficient.
- Preserve the acquisition agreement and contract dates.
- Document when the property became ready and available for rent.
- Verify each component’s classification and business use.
- Keep the building structure outside the bonus calculation.
- Ask your CPA to review elections and state conformity.
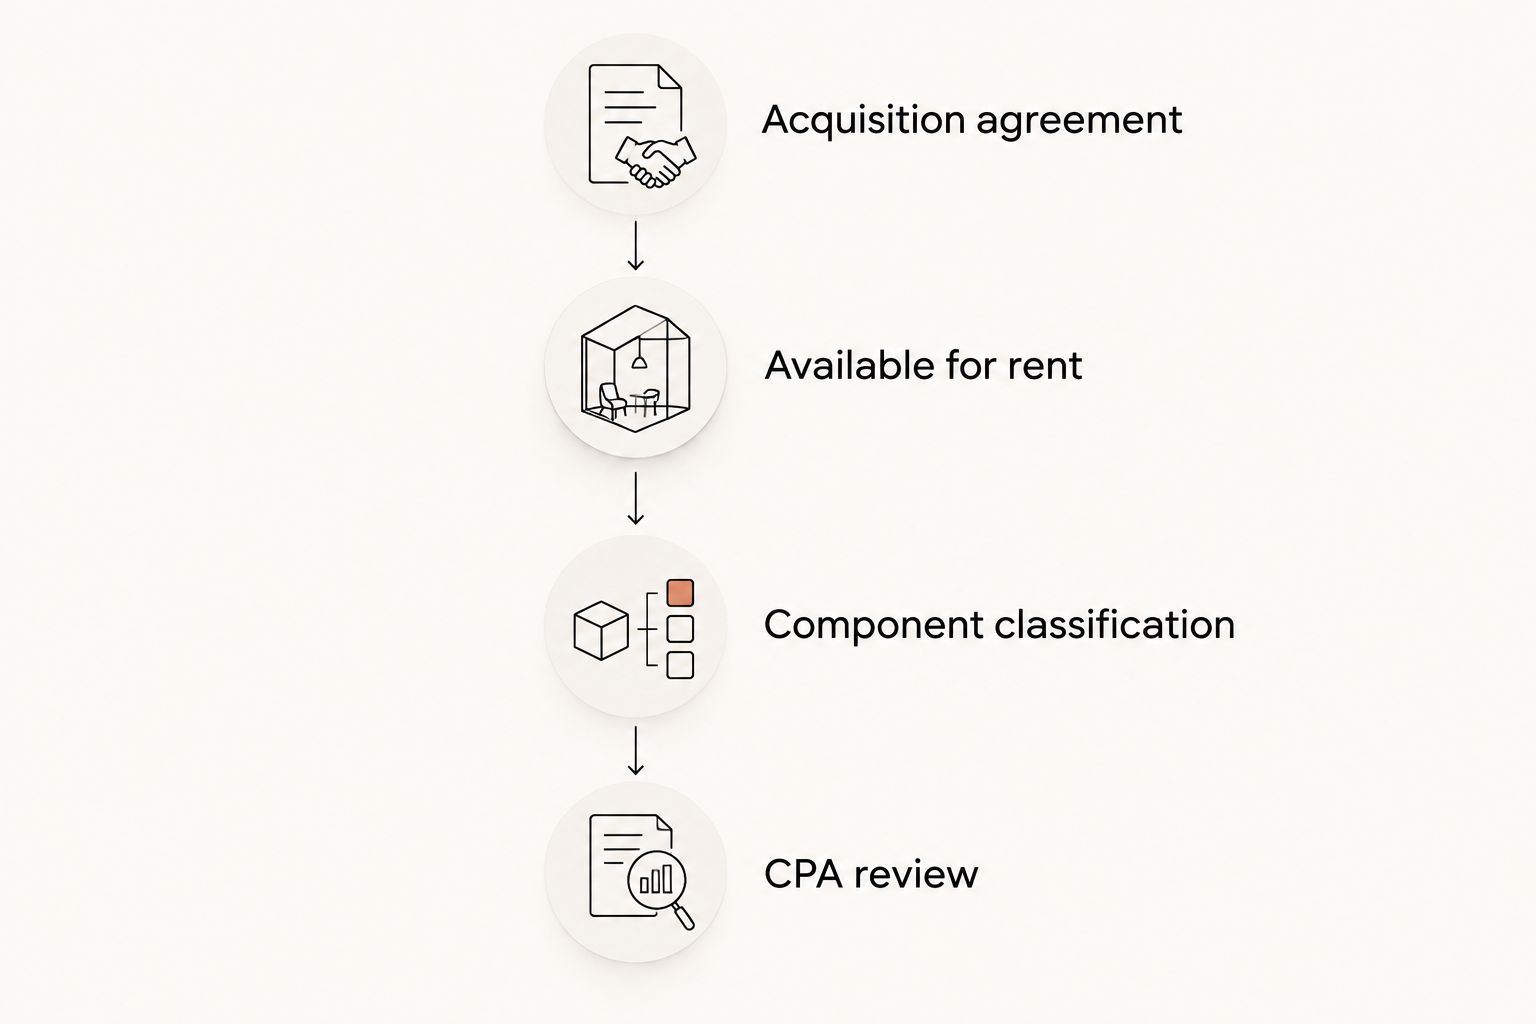
For a home bought before January 20, 2025 and converted to a rental later, conversion does not reset its acquisition date. It does not receive the restored full bonus treatment merely because rental use begins later; the applicable rate depends on the purchase date and should be confirmed with your CPA.
5. Model usable deductions rather than headline savings
Build an illustrative model before treating an estimate as a tax-payment decision. Assume 25% of depreciable rental-property value is reclassified and a 37% federal marginal bracket. Those are modeling assumptions, not a prediction of your study’s findings.
For every illustrative $100 of depreciable basis, that assumption assigns $25 to shorter-lived components. If the entire $25 is deductible currently and offsets income otherwise taxed at 37%, the arithmetic produces $9.25 of federal tax reduction before other effects. That is not the incremental benefit over ordinary depreciation, which would also provide deductions.
Your CPA’s comparison must subtract depreciation otherwise available, test current loss usability, and consider later years. Accelerating deductions changes timing and can affect depreciation recapture when you sell.
- Label the 25% allocation as illustrative.
- Apply the assumed 37% bracket only where appropriate.
- Compare accelerated depreciation with the ordinary schedule.
- Separate federal effects from state effects.
- Include holding period and potential sale consequences.
6. Coordinate filing and preserve the evidence
Have your CPA review the study before finalizing your 2026 return or adjusting withholding. Reconcile asset totals to basis and check that furnishings or improvements already on the books are not counted again.
For a look-back study, missed depreciation is claimed on the current return with Form 3115 and a Section 481(a) adjustment; prior returns are not amended for that catch-up. Your CPA must determine the applicable accounting-method-change procedures and filing requirements.
Virtual Cost Segregation provides Form 3115 on request; your CPA files it. The study itself is not filed with the IRS. Preserve the report alongside the underlying purchase documents, invoices, booking data, and participation records.
- Reconcile the study with existing depreciation schedules.
- Ask your CPA to determine Form 4562 reporting.
- Review Form 3115 requirements for a look-back study.
- Retain evidence supporting rental readiness and participation.
- Revisit the projection after actual commissions are known.
Request a residential rental estimate
Ask for a free manual savings estimate, then review the assumptions with your CPA.
Compare your depreciation-planning options
Choose support based on the decision you need to make. An estimate helps screen a property; a study supports component classification; your CPA applies tax law to the return. These roles complement one another rather than replace one another.
| Option | Best for | Practical benefit | Key limitation |
|---|---|---|---|
| Ordinary depreciation with CPA review | Owners prioritizing a conventional schedule | Preserves an established filing approach | Does not identify additional shorter-lived components through a study |
| Manual estimate or calculator | Owners screening potential study value | Supports an initial planning discussion | Does not establish asset classifications or usable tax benefits |
| Virtual Cost Segregation engineering-based study | Residential rental owners needing component-level study support | Provides a CPA-ready report without a site visit | Does not determine personal loss eligibility or replace your CPA |
| CPA implementation and tax projection | Sales executives deciding how deductions affect compensation taxes | Connects the study to limitations, elections, and filing | Requires accurate owner records and study inputs |
For a sales executive evaluating 2026 commission income, start with the tax projection rather than the largest estimated deduction. If losses remain suspended, a study can still accelerate depreciation, but its current cash-tax value differs from a usable W-2 offset.
Common mistakes sales executives make
Treating a commission spike as eligibility
A high tax bracket increases the potential value of an allowed deduction. It does not turn a passive rental loss into a compensation offset. Ask your CPA to resolve loss treatment before comparing projected savings with study costs.
Outsourcing operations but claiming personal participation
A manager’s work is not your work. Under the more-than-100-hours test discussed above, your participation must also exceed every other individual’s participation. Keep task-based records and confirm the relevant facts rather than assuming ownership establishes involvement.
Confusing study delivery with rental readiness
A completed report does not establish when property was placed in service. Rental readiness depends on the property’s actual condition and availability. Preserve listing records, completion documentation, and other evidence your CPA requests.
Treating a renovation invoice as one short-lived asset
A theater room, outdoor amenity, or furnishing package can contain components with different tax treatment. Classification depends on function, documentation, placed-in-service timing, and taxpayer facts. Do not assign an entire project a recovery period based on its marketing name.
Spending the projected tax reduction before filing
An estimate is not spendable cash. Withholding, other income, state rules, and deduction limits affect the final return. Keep operating reserves separate from an anticipated tax reduction, especially when commissions fluctuate.
FAQ
Can cost segregation offset my sales commissions?
Cost segregation can generate rental deductions that offset W-2 commissions only when the applicable tax rules permit their current use against that income. For a qualifying short-term rental, average stays and material participation are central, and other loss limitations still require CPA review.
Do I need real estate professional status if I work in sales?
Real estate professional status is not required for the commonly used short-term-rental approach involving average stays of 7 days or less and material participation. Your CPA must confirm that the activity satisfies the relevant requirements; ownership alone is insufficient.
Is more than 100 hours enough if I hire a property manager?
More than 100 hours alone does not satisfy the commonly used participation test discussed here. Your participation must also exceed that of every other individual, including the property manager, unless you satisfy another applicable material-participation test.
Does a rental purchased in 2026 qualify for full bonus depreciation?
Eligible property acquired and placed in service after January 19, 2025 qualifies for 100% bonus depreciation, subject to applicable requirements. The building structure is excluded, and your CPA must verify acquisition timing, component eligibility, and any relevant elections.
Can I use cost segregation on a long-term residential rental?
Yes, a long-term residential rental can support cost segregation of qualifying components. Accelerated deductions do not automatically offset W-2 compensation because passive-activity and other loss limitations still apply.
Can I order a study for a rental I already own?
Yes, an existing residential rental can be evaluated through a look-back study. Missed depreciation is claimed on the current return with Form 3115 and a Section 481(a) adjustment, rather than by amending prior returns for that catch-up; your CPA handles the filing requirements.
Will Virtual Cost Segregation prepare my tax return?
No, Virtual Cost Segregation supplies a supplementary engineering-based study, not CPA services or tax-return preparation. Your own CPA applies the findings, determines deductions, and handles the required filings.
One last thing
Your most valuable pre-study document can be the operating record, not the property appraisal. A component classification supports depreciation, but it cannot establish your material participation.
Before pursuing a larger deduction, ask your CPA one precise question: which portion of the proposed rental loss is usable against my 2026 compensation? That answer separates tax planning from a deduction that remains on a carryforward schedule.
This guide provides general educational information, not individualized tax advice. Apply current law to your property, participation, and return with your CPA.