By Virtual Cost Segregation
The best cost segregation study provider for rental property investors
 Built to IRS standards
 Audit support includedFlat price for every study3 to 5 business days
Management consultants’ cost segregation is the classification of residential rental components into shorter depreciation lives with the aim of accelerating eligible tax deductions. Cost segregation for management consultants starts with a separate question: whether your rental losses can offset consulting income, given your rental operations, participation, and tax limitations.
- Cost segregation for management consultants accelerates residential rental depreciation; usable deductions depend on participation and tax limitations.
- Virtual Cost Segregation suits residential rental owners seeking an engineering-based study for their CPA to implement.
- Short-term rental owners need guest-stay records and material participation evidence before planning a W-2 offset.
- Separate bonus depreciation eligibility from passive-loss treatment; satisfying one does not establish the other.
Why cost segregation matters for management consultants
Your occupation does not make rental losses deductible against your consulting income. A management consultant employed on a W-2 and an independent consultant reporting business income both need a rental-specific tax analysis. A larger depreciation deduction does not bypass passive activity rules.
For your 2026 planning, separate deduction size from deduction usability. The guide for high-income W-2 earners explains the income-offset question; the steps below connect that question to rental operations, documentation, and CPA implementation.
If you outsource guest communication, maintenance, and turnovers, account for those individuals’ work when evaluating material participation. Do not plan around hours you expect to work. Establish what your records support.
How to evaluate and implement a residential study
Establish your rental’s tax profile
Start with a spreadsheet and your existing tax records. Identify the owner, rental use, depreciable basis, acquisition date, and placed-in-service date before requesting a study. The placed-in-service date generally reflects when the property was ready and available for rental use, not simply when you closed.
Keep the building’s recovery period separate from the home’s physical appearance. A long-term rental building generally uses a 27.5-year recovery period. A short-term rental building with average stays under 30 days uses a 39-year recovery period under the treatment addressed here, including the 7-day-average STR strategy. Your CPA must apply the classification to the actual facts.
Neither building structure qualifies for bonus depreciation. Cost segregation identifies eligible components separately; it does not turn the entire house into short-life property. Land is not depreciable.
For a property converted from personal use, give your CPA both acquisition records and conversion information. Converting the home in 2026 does not reset its acquisition date.
- Record the legal owner and your ownership percentage.
- Separate land from depreciable property basis.
- Preserve the purchase contract and closing statement.
- Record rental availability, guest stays, and personal-use days.
- Identify improvements separately from the original acquisition.
Test whether you can use the rental loss
Calculate average guest stays from booking records, then review material participation with your CPA. Under the commonly discussed short-term rental exception, average guest stays must be 7 days or less, together with material participation, for the intended nonpassive treatment. Real estate professional status is not required for that route.
One common material participation test requires more than 100 hours of participation and more participation than any other individual, including a property manager. More than 100 hours alone is not enough. Other tests exist, and your CPA should identify the applicable test rather than treating this threshold as the only route.
Consulting work hours do not count as rental participation. Document rental tasks separately, and distinguish operational work from investor activities that do not count. A demanding consulting schedule does not establish or disprove qualification; the rental facts control.
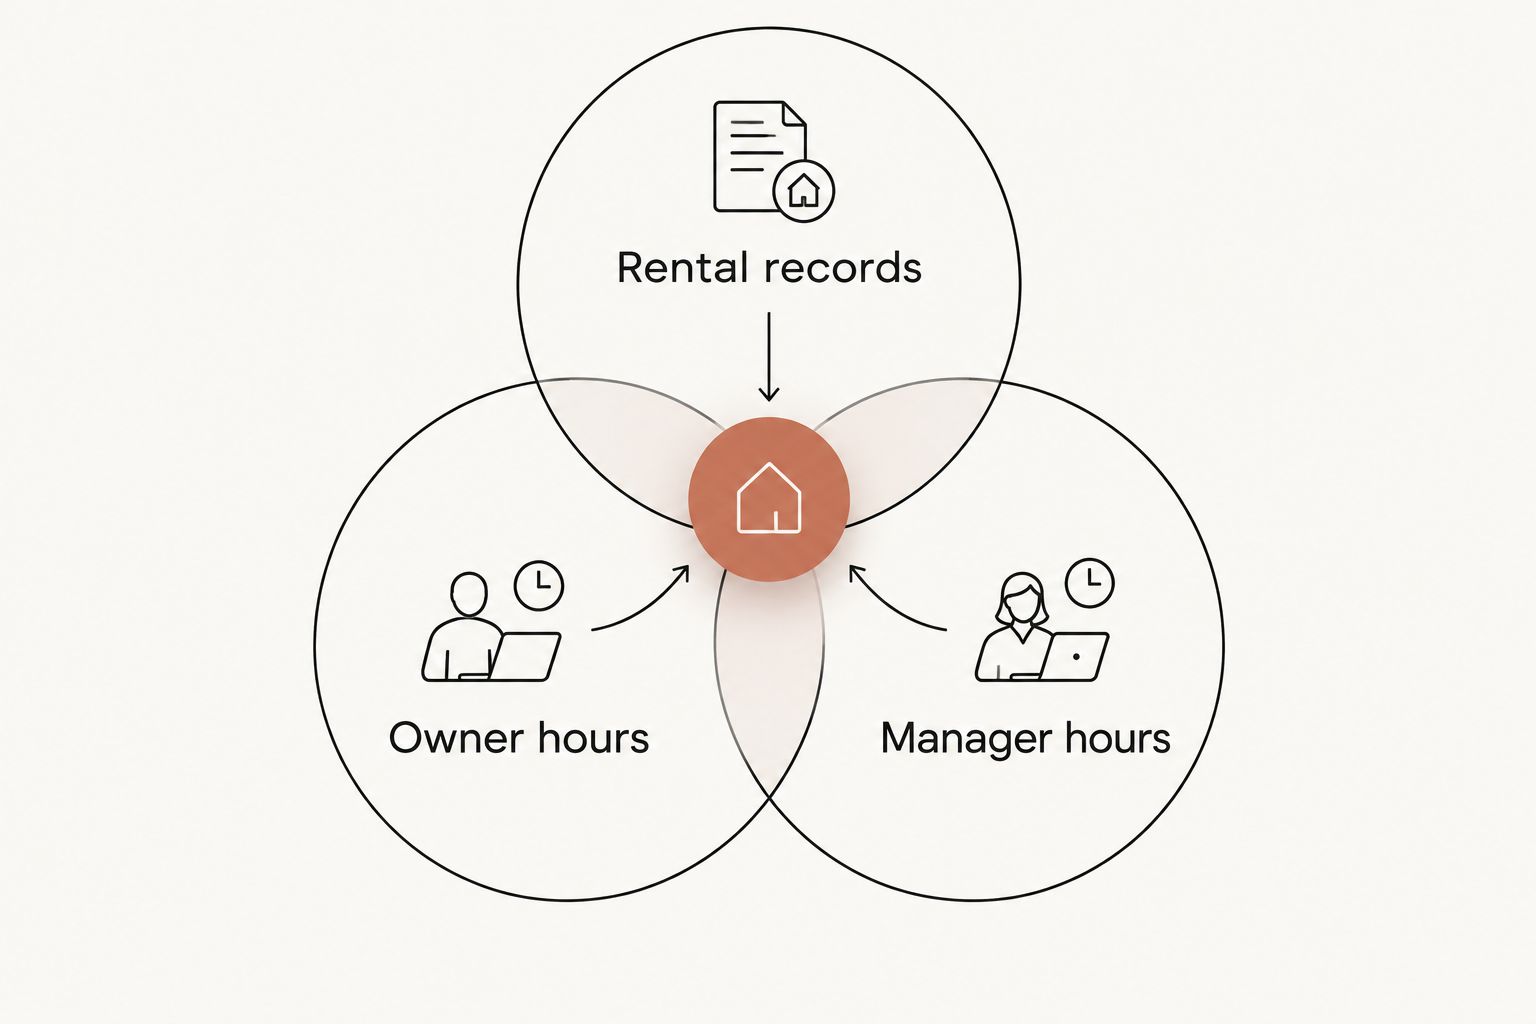
Use these records together rather than treating your own time log as the entire analysis:
- Rental records: calculate average stays from actual bookings.
- Owner hours: record dates, tasks, and time spent.
- Manager hours: obtain support for outsourced participation.
- Supporting evidence: retain messages, invoices, and calendars.
Assemble the evidence before ordering a study
Build a shared document folder first. Include purchase records, existing depreciation schedules, renovation invoices, and photographs that explain the rental’s components. For an older rental, reconcile the basis already being depreciated before adding a new classification schedule.
A calculator supplies a preliminary estimate, not an engineering-based allocation. It cannot replace evidence showing what assets exist, how they function, and how their costs were determined.
Virtual Cost Segregation provides engineering-based cost segregation studies for residential rentals of 1 to 4 units, with no site visit required. Delivery is 3 to 5 business days, and audit support is included. The study supplies the classification report; your CPA determines how to apply it on your return.
You can contact the team for a free manual savings estimate. Treat that estimate as a planning input, not an established deduction or tax outcome.
- Collect the closing statement and purchase agreement.
- Export the current depreciation schedule from your tax records.
- Match renovation invoices to completed work.
- Separate furniture purchases from costs already in the acquisition basis.
- Flag missing records before accepting an estimated benefit.
Verify bonus eligibility asset by asset
For 2026 planning, eligible property acquired and placed in service after January 19, 2025 qualifies for 100% bonus depreciation, subject to the applicable requirements. Both dates matter. The restored rate has no scheduled phase-down or end date.
Do not substitute the study completion date for either tax date. A binding purchase contract signed before January 20, 2025 can affect the acquisition analysis even when closing occurred later. Ask your CPA to review the contract rather than relying only on the closing statement.
A home purchased before January 20, 2025 and converted to a rental later does not receive the restored full rate merely because of conversion. Its treatment depends on the purchase date and applicable rules; have your CPA confirm it without assuming a rate.
Even without bonus depreciation, eligible components can receive accelerated deductions through 5-, 7-, and 15-year recovery periods. Classification depends on each asset’s function and documentation. Do not assign an entire amenity or renovation to one recovery period simply because some components qualify.
- Confirm acquisition and placed-in-service dates separately.
- Give your CPA any earlier binding contract.
- Review each asset’s function and supporting documentation.
- Keep building structure outside the bonus-eligible allocation.
- Check state treatment separately from federal treatment.
Model usable tax savings instead of headline deductions
Use a spreadsheet to compare ordinary depreciation with the proposed classification. Include the year you can actually deduct the loss, state treatment, implementation expenses, and your expected ownership period. A deduction suspended under passive-loss rules has a different cash-flow effect from one usable on your current return.
Illustrative math: assume a residential rental has $400,000 of depreciable basis after excluding land. Assume 25% is reclassified, producing $100,000 of shorter-life components. This is an example, not a prediction of your study’s allocation; results vary.
At an assumed 37% marginal federal bracket, a hypothetical $100,000 currently deductible amount has a $37,000 federal tax effect before other interactions. That is not automatically the incremental benefit of the study. You must subtract depreciation otherwise available and account for deduction timing and limitations.
For your 2026 decision, ask for the comparison rather than the largest deduction shown on an estimate. Accelerating deductions also reduces remaining basis, and a later sale requires analysis of depreciation recapture and other gain treatment.
- Compare the study result with depreciation otherwise available.
- Separate current deductions from suspended losses.
- Apply your actual federal and state tax circumstances.
- Include study and CPA implementation expenses.
- Review sale timing and potential recapture with your CPA.
Hand the report to your CPA for implementation
Arrange the handoff before your filing deadline. Your CPA needs the report, reconciled basis, prior depreciation, acquisition dates, rental-use records, and participation documentation. A study does not establish material participation or replace the return preparer’s tax analysis.
For a current-year acquisition, your CPA generally implements depreciation through the asset schedules and Form 4562. For a qualifying look-back study involving an accounting-method change, missed depreciation is claimed on the current return through Form 3115 and a Section 481(a) adjustment; prior returns are not amended for that catch-up process.
Virtual Cost Segregation is not a CPA service. The report is supplementary and is not itself filed with the IRS. Form 3115 is provided on request, and your CPA handles filing and determines the applicable method-change requirements.
Close the 2026 workflow with written confirmation of implementation, not merely receipt of the report. The final schedules should reconcile to your records without duplicating separately purchased assets.
- Reconcile total allocated costs to depreciable basis.
- Identify assets already depreciated separately.
- Confirm current-year or look-back implementation.
- Ask the CPA to review federal and state differences.
- Retain the report with source documents and filed schedules.
Compare your implementation options
Choose the option that matches your decision stage. Preliminary screening, asset classification, and tax filing are different jobs; hiring one provider does not eliminate the others.
| Option | Best for | Main advantage | Key limitation |
|---|---|---|---|
| Manual spreadsheet review | Consultants screening a potential rental deduction | Organizes basis, dates, and participation evidence | Does not produce an engineering-based asset allocation |
| DIY calculator | Owners seeking an initial directional estimate | Helps frame questions before ordering a study | Estimated allocations do not establish property-specific classifications |
| Virtual Cost Segregation engineering-based study | Owners of residential rentals with 1 to 4 units seeking a CPA-ready report | No site visit required; audit support included | Does not determine your loss eligibility or replace CPA implementation |
| CPA tax review and implementation | Owners deciding how deductions apply to their return | Connects the report to limitations, elections, and filing requirements | Tax review alone does not replace an engineering-based study |
Virtual Cost Segregation is best for residential rental owners seeking an engineering-based cost segregation report for their own CPA to implement. Order after the tax-use analysis, not instead of it.
Common mistakes management consultants make
Treating a high tax bracket as eligibility
A high bracket increases the value of a usable deduction, not the right to claim it against consulting income. Ask your CPA to identify the income category the rental loss can offset before evaluating the study’s projected benefit.
Counting only your own participation
A consultant who logs rental work but ignores a co-host’s or manager’s hours has an incomplete record for the more-than-any-other-individual test. Obtain evidence of outsourced work before relying on that test.
Using the purchase date as the entire timeline
Closing, rental readiness, renovation completion, and acquisition under a binding contract are distinct facts. Keep the documents together so your CPA can evaluate the correct dates for each asset.
Treating accelerated depreciation as permanent tax elimination
Cost segregation changes deduction timing. A suspended loss, reduced future depreciation, or later recapture changes the economics, so compare the holding-period outcome rather than presenting the first-year deduction as the entire benefit.
FAQ
Can management consultants use cost segregation to offset W-2 income?
A management consultant’s rental loss can offset W-2 income only when the applicable activity and loss-limitation rules permit it. A cost segregation study accelerates eligible depreciation but does not establish nonpassive treatment or material participation.
Do I need real estate professional status for a short-term rental strategy?
Real estate professional status is not required for the short-term rental route involving average guest stays of 7 days or less and material participation. Your CPA must evaluate both the rental activity and your participation under the applicable rules.
Is working more than 100 hours on my rental enough?
More than 100 hours alone is not enough under the commonly used comparative participation test. That test also requires more participation than any other individual, including a property manager; your CPA should evaluate which test applies.
Does a residential rental building qualify for bonus depreciation?
The building structure does not qualify for bonus depreciation. A cost segregation study separates eligible shorter-life components from the structure, with classification and bonus eligibility determined from asset function, documentation, dates, and taxpayer facts.
Can I order a study for a rental I already own?
An existing residential rental can be evaluated through a look-back study. For a qualifying accounting-method change, your CPA claims missed depreciation on the current return using Form 3115 and a Section 481(a) adjustment rather than amending prior returns for that catch-up process.
Does Virtual Cost Segregation file my tax return?
Virtual Cost Segregation supplies the engineering-based study, not CPA tax preparation. Your own CPA applies the report when filing; the study itself is not filed with the IRS.
What happens if my consulting schedule leaves little time for rental work?
Your actual rental participation determines whether you satisfy an applicable material participation test. Do not count consulting hours as rental work or assume ownership alone supports nonpassive treatment.
One last thing
The most useful pre-study question is about usable losses, not allocation percentages. Ask your CPA which income a rental loss can offset in 2026 and what evidence supports that answer. Then request a study estimate against that tax position, rather than building a tax position around an estimate.
This guide provides general educational information. Apply current law to your own facts with your tax professional.