By Virtual Cost Segregation
The best cost segregation study provider for rental property investors
 Built to IRS standards
 Audit support includedFlat price for every study3 to 5 business days
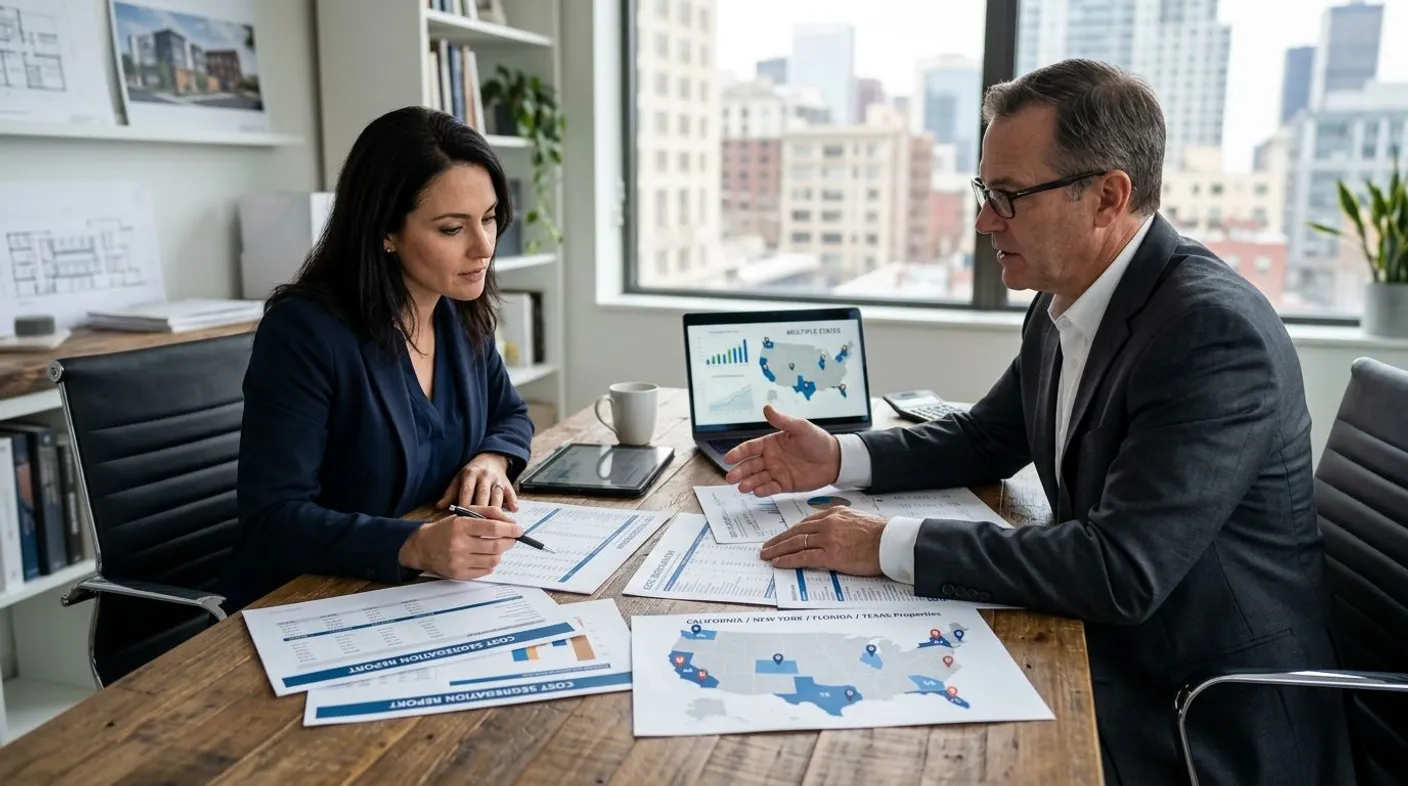
Cost segregation for multi-state landlords works property by property, not portfolio by portfolio. Each rental you own in Texas, California, Colorado, or anywhere else needs its own engineering-based study because depreciation rules apply at the asset level, and state tax conformity to federal bonus depreciation varies widely.
- Cost segregation for multi-state landlords requires a separate study per property, not one blended report across states.
- Virtual Cost Segregation runs flat-fee remote studies at $2,200 per property with no site visit required, useful when assets sit in different states.
- Federal bonus depreciation is 100% for property acquired and placed in service after January 19, 2025 under the OBBBA, but state conformity differs by state.
- A study commonly reclassifies around 25% of property value into 5, 7, and 15-year assets, accelerating year-one deductions.
- Track material participation days separately per property if you use the STR loophole across a multi-state portfolio.
Why cost segregation matters for landlords with rentals in multiple states
Owning rentals across state lines multiplies your paperwork, but the federal benefit of cost segregation does not change with geography. A single-family rental in Ohio and a short-term rental in Arizona both qualify for the same accelerated depreciation treatment under IRS rules, as long as each one is residential rental property placed in service and actively used for business.
What changes state to state is the state income tax layer. States like Texas, Florida, and Washington have no state income tax, so a study delivers its value at the federal level with no state offset to plan around. Other states decouple partially from federal bonus depreciation, meaning your state return may not mirror the accelerated federal deduction dollar for dollar in year one.
That gap is why landlords running a multi-property Airbnb portfolio need a state-by-state plan instead of one blanket assumption. Guessing at conformity rules is how landlords end up amending returns in 2026 that they filed cleanly the first time.
Inventory every property before you order anything
Start with a full list. Landlords with 3, 5, or 10 properties across different states routinely lose track of placed-in-service dates, purchase prices, and renovation history at the individual property level.
- List each property's state, purchase date, and purchase price separately
- Record the placed-in-service date for each one, since bonus depreciation eligibility turns on that date under OBBBA
- Flag properties bought in a bundled or portfolio acquisition, where purchase price allocation gets complicated
- Separate short-term rentals (Airbnb, VRBO) from long-term residential rentals, since the STR loophole applies only to the former
- Mark lower-value properties separately, since the ROI math on a study looks different at smaller purchase prices
A cost segregation study is always done at the property level, and a study for out-of-state rental owners is built around this exact constraint, since the engineer never needs to stand on the property.
Match each property to the right study timing
Not every property in your portfolio carries the same urgency. A property you have owned for eight years may benefit from a look-back study paired with Form 3115 to catch up missed depreciation in a single year, while a property closing this quarter benefits from a study timed before the filing deadline.
- Consider a look-back study on properties held several years without a prior study
- Order a study in the first year for newly acquired or newly renovated properties
- Exclude commercial property types entirely, since residential studies cover single-family, duplex, condo, townhome, and short-term rental properties
- Note any property that changed use mid-year, such as a primary residence converted to a rental
- Confirm each property is actively held out for rent, not vacant or mid-construction
Track state depreciation conformity differences
This is the step most multi-state landlords skip, and it surfaces at filing time. Federal bonus depreciation is 100% for qualifying property acquired and placed in service after January 19, 2025, but several states require an addback or a separate state depreciation schedule.
- Ask your CPA which states in your portfolio decouple from federal bonus depreciation
- Keep separate depreciation schedules per state if your CPA files multiple state returns
- Confirm whether a state requires an addition or subtraction adjustment for accelerated depreciation taken federally
- Check how each state treats rental income for short-term versus long-term rental classification
- Keep each property's state-specific treatment in your own records, not only inside your CPA's software
A CPA coordinating across states benefits from a remote provider for out-of-state investors, because the reports arrive in the same standardized format no matter which state the property sits in.
Confirm placed-in-service dates across acquisitions
If you bought three properties in three states during 2026, each has its own placed-in-service date, and that date drives bonus depreciation eligibility.
- Pull the closing statement for every acquisition to confirm the exact date
- Separate any property that needed renovation before it was rent-ready, since the in-service date shifts to when it was available for tenants
- Flag properties acquired through a 1031 exchange, where the depreciable basis calculation differs from a standard purchase
- Note properties acquired via seller financing or at auction, where closing paperwork is often less standardized
Allocate purchase price correctly on portfolio deals
Landlords who buy several properties in one transaction, common when entering a new state through a bulk deal, often skip proper purchase price allocation. That mistake distorts depreciable basis on every property in the deal.
- Get a separate valuation or allocation schedule for each property in a bundled purchase
- Avoid splitting the purchase price evenly when property values clearly differ
- Document land value separately for each property, since land never depreciates
- Review how to allocate purchase price across a portfolio acquisition before your CPA files
Track material participation days per property
Landlords running short-term rentals in multiple states to offset W-2 income need to track time per property. Hours are not simply averaged across a portfolio; material participation is tested per activity, and grouping decisions matter.
- Log hours for each property individually: guest communication, cleaning coordination, maintenance calls
- Keep a contemporaneous time log rather than reconstructing hours in April
- Ask your CPA whether your properties can be grouped as a single activity for material participation purposes
- Separate properties handled by a third-party property manager, since that changes how your hours are counted
Choose a study process built for remote portfolios
A landlord with properties in four states cannot schedule four site visits. An engineering-based study built on property records, permits, construction documentation, and imagery works the same whether the rental is 50 miles away or 2,000.
- Confirm the provider does not require an in-person site visit per property
- Ask for turnaround per property; an engineering-based flat-fee study typically completes in 3 to 5 business days
- Request a CPA-ready report your accountant can implement on Form 4562 without reformatting
- Compare flat-fee pricing per property against percentage-of-savings pricing, which scales badly across many properties
Virtual Cost Segregation delivers flat-fee, engineering-based cost segregation studies at $2,200 per property with no site visit required and 3 to 5 business day turnaround, which fits landlords holding residential rentals across several states.
Start a study for your portfolio
Flat-fee engineering-based studies for each residential rental you own, in any state.
Comparison of options for multi-state landlords
| Option | Best for | Key limitation |
|---|---|---|
| DIY depreciation calculator | A rough estimate before committing to anything | Not audit-defensible, no engineering documentation |
| Flat-fee engineering-based study | Landlords with 2 or more residential rentals across states | Requires coordination with your own CPA to implement |
| Percentage-of-savings firm | Investors who prefer contingent pricing | Fee scales with savings, costly across many properties |
| Low-cost or overseas-prepared study | Lowest sticker price | Thinner audit documentation and inconsistent turnaround |
Verdict: a flat-fee, remote, engineering-based study per property is the most practical route for a landlord holding rentals in three or more states in 2026, because cost and turnaround stay predictable regardless of location.
Common mistakes multi-state landlords make
- Treating the portfolio as one study. Each property needs its own report; there is no combined multi-state study.
- Assuming state depreciation mirrors federal. Several states do not fully conform to 100% bonus depreciation, and each property's state needs flagging in advance.
- Mixing up placed-in-service dates across a busy acquisition year. That date decides bonus depreciation eligibility under OBBBA.
- Averaging material participation hours across properties. Participation is tested per activity, not as a portfolio average.
- Waiting until filing season to order every study at once. Staggering studies across 2026, timed to each placed-in-service date, avoids a year-end pile-up across multiple state returns.
FAQ
What is cost segregation for multi-state landlords?
It is ordering a separate engineering-based cost segregation study for each residential rental you own across different states. Depreciation applies at the property level, so one report cannot cover a whole portfolio.
Do state depreciation rules differ from federal bonus depreciation?
Yes. Federal bonus depreciation is 100% for qualifying property acquired and placed in service after January 19, 2025 under the OBBBA, but several states decouple and require separate state depreciation schedules.
Can one cost segregation study cover properties in multiple states?
No. Each property gets its own study because purchase price, construction detail, and placed-in-service date are unique to that asset, even when one LLC owns all of them.
Does owning a rental in a no-income-tax state change the value of cost segregation?
The federal benefit is the same everywhere. In states without income tax, such as Texas, Florida, and Washington, there is simply no state-level adjustment to plan around.
How much does a cost segregation study cost per property?
Virtual Cost Segregation charges a flat $2,200 per property and includes support if the return is audited. Pricing does not change based on which state the rental is in.
Do I need a study for every property I own?
Not necessarily. Lower-value properties or ones you plan to sell soon may not generate enough reclassified basis to justify the fee, so run the estimate property by property first.
How long does a cost segregation study take for out-of-state properties?
An engineering-based remote study typically completes in 3 to 5 business days per property. No site visit is required, so distance does not extend the timeline.
Is a site visit required for out-of-state rentals?
No. An engineering-based study uses property records, permits, closing documents, and imagery instead of an in-person visit, which is what makes multi-state portfolios workable at all.
One last thing
Landlords tend to picture a multi-state portfolio as one large tax problem. It is several separate problems that happen to share a Schedule E. On a $500,000 residential rental with roughly 25% of value reclassified into 5, 7, and 15-year assets, an owner in the 37% bracket is looking at an estimated first-year deduction around $125,000 and an estimated federal tax effect near $46,250. Those figures are illustrative averages, not a guarantee, and they shift with construction type, state conformity, and the placed-in-service date. Run the estimate per property before you assume the rest of the portfolio behaves the same way.