By Virtual Cost Segregation
The best cost segregation study provider for rental property investors
 Built to IRS standards
 Audit support includedFlat price for every study3 to 5 business days
Cost segregation for self-managing landlords is a tax strategy that reclassifies parts of a rental property into shorter depreciation schedules (5, 7, and 15-year property) instead of writing off the whole structure over 27.5 or 39 years. Self-managing landlords carry a specific burden other owners don't: there's no property manager tracking capital expenses on your behalf, so every receipt, floor plan, and placed-in-service date has to come from you.
- Cost segregation for self-managing landlords reclassifies 20-45% of a residential property's basis into 5, 7, and 15-year property.
- Bonus depreciation sits at 100% permanently for property acquired and placed in service after January 19, 2025 under OBBBA.
- Self-managing owners need their own documentation system since no property manager is tracking capital expenses for them.
- A flat-fee, engineering-based study from Virtual Cost Segregation takes 3-5 business days and includes audit support.
- Skipping the study on a self-managed portfolio usually means leaving five-figure first-year deductions on the table.
Why cost segregation matters for self-managing landlords
If you're managing your own units, you're already doing the work a property management company would normally outsource: screening tenants, handling turnovers, tracking tax deductions for self-managed rental owners, and reconciling your own books at tax time. That means the depreciation schedule your CPA files is only as good as the records you hand over.
Most self-managing landlords default to straight-line depreciation because nobody on their team flags the alternative. A single-family rental or short-term rental bought for $500,000 depreciated straight-line gets roughly $18,000 a year written off the structure. An engineering-based study that reclassifies 25% of that basis into 5, 7, and 15-year buckets can move a much larger chunk of that value into year one, especially with bonus depreciation restored to 100% under the One Big Beautiful Bill Act for anything acquired and placed in service after January 19, 2025. For an owner in the 37% tax bracket, that first-year shift is the difference between a modest deduction and one that materially changes the tax bill.
The catch: self-managing landlords rarely have a bookkeeper separating capital improvements from repairs in real time, which is exactly the documentation an IRS examiner or CPA needs before applying a study.
Build your documentation and study process
Track your capital expenses like a portfolio, not a shoebox
Self-managed owners often log expenses property-by-property in whatever app came free with their bank account. That works until you're trying to reconstruct which HVAC replacement happened in which tax year.
- Keep a running ledger per property, not one combined file for the whole portfolio
- Separate "repair" line items (fixing a leak) from "capital improvement" line items (new roof, new flooring)
- Save every invoice with the date the work was completed, not just the date it was paid
- Note the placed-in-service date for any new asset, since that date drives bonus depreciation eligibility
- Store contractor W-9s and scopes of work alongside the invoice, in case a study needs backup
Separate repairs from capital improvements before you file
This is where most self-managing landlords lose deductions or invite scrutiny. Repairs are deductible in the year paid; capital improvements get depreciated. Mixing the two on a Schedule E is a common audit trigger.
- Use the IRS routine maintenance safe harbor for recurring small-dollar work
- Flag anything over $2,500 (the de minimis safe harbor threshold many owners elect) for separate tracking
- Document the condition of the asset before and after the work with photos
- Ask your CPA to confirm your capitalization policy is in writing and applied consistently across the portfolio
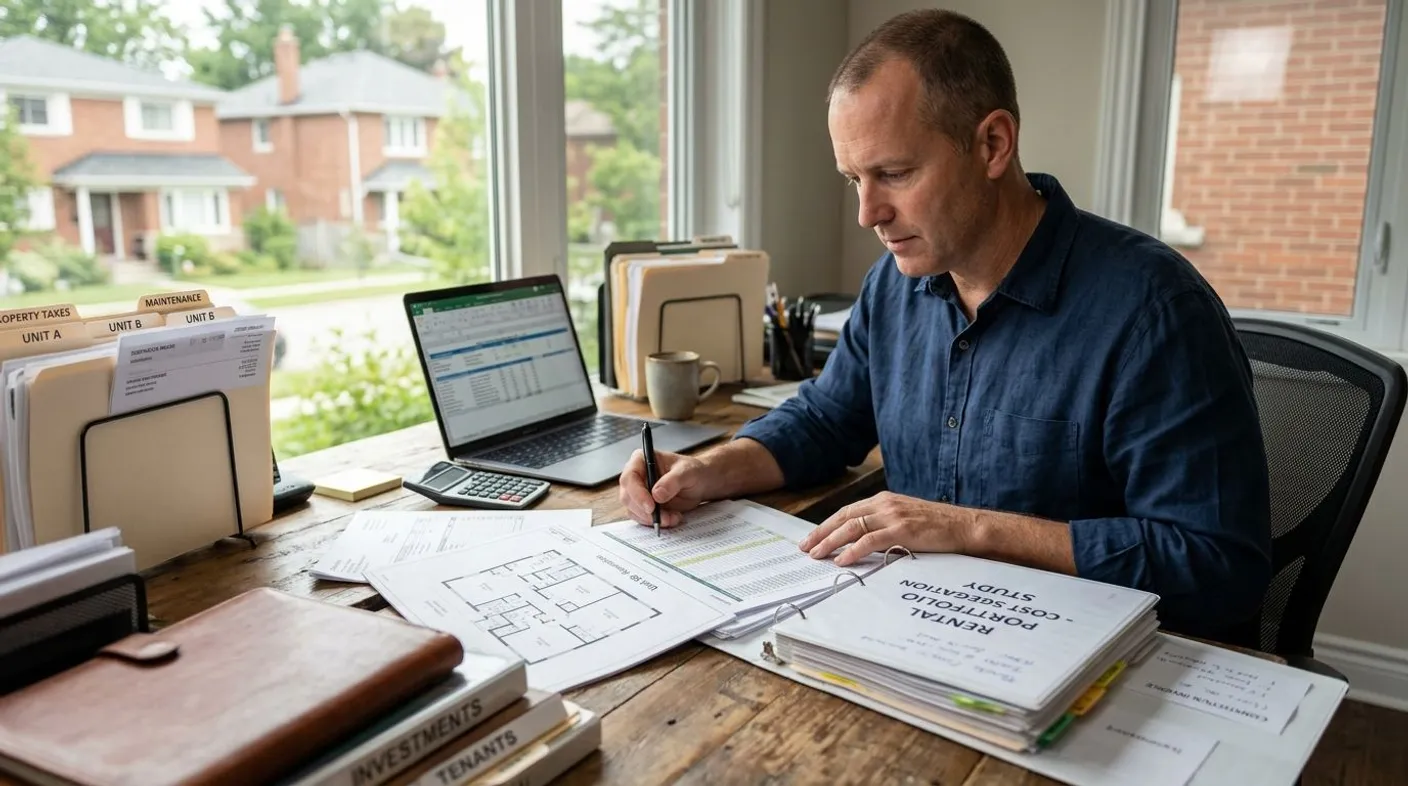
Build a floor plan and photo file for every property you self-manage
An engineering-based cost segregation study needs a floor plan, photos, and a purchase settlement statement. Self-managing landlords who already handle guest turnovers or tenant walkthroughs usually have most of this on hand, they just haven't organized it.
- Pull the settlement statement or closing disclosure from the purchase
- Photograph interior finishes, exterior land improvements (decks, fencing, parking), and any furnished rental equipment
- Keep renovation permits and contractor invoices in one folder per property
- Note square footage breakdowns if the property has an accessory dwelling unit or a duplex/triplex configuration
Time your study around placed-in-service dates and 100% bonus depreciation
The purchase date and the placed-in-service date together determine what bonus depreciation rate applies. Property acquired and placed in service after January 19, 2025 qualifies for the 100% rate under OBBBA, which is now the permanent rule rather than a temporary one.
- Confirm the exact placed-in-service date for each property in your portfolio
- Order a study before you file, not after an extension deadline has already passed
- For properties owned for years without a prior study, ask about a look-back study combined with Form 3115 to catch up missed depreciation without amending old returns
- Coordinate timing with any planned renovations, since a mid-renovation study captures different assets than a post-renovation one
Coordinate the study with your CPA before ordering
A cost segregation report is not a CPA service and isn't filed directly with the IRS. It's a supplementary, audit-defensible report your CPA applies to your return. Self-managing landlords sometimes skip this step and hand the CPA a report after the return is already drafted.
- Loop in your CPA before the study starts so they know what depreciation method changes to expect
- Ask whether a Form 3115 accounting method change applies to your situation
- Confirm which entity structure (LLC, personal name, trust) holds each property, since that affects how the study gets applied
- Review the property qualification criteria before ordering, since not every property benefits equally
Keep records your CPA and an auditor can both use
Self-managing landlords who skip this step end up scrambling if a return gets reviewed. Recordkeeping for a cost segregation study is the difference between a report that holds up and one that gets challenged.
- Keep the full cost segregation report, not just the summary page, for as long as the asset is depreciated
- Store the report alongside Form 4562 and any Form 3115 filed for the same property
- Retain photos and floor plans used in the study, since they support the asset classifications if questioned
- Update records each time you renovate, since new capital improvements may need their own partial asset disposition or reclassification
Run the ROI math before you order anything
Not every property benefits equally from cost segregation. A $180,000 property with few reclassifiable components won't move the needle the way a furnished short-term rental with a pool, hot tub, and outdoor kitchen will.
- Estimate the reclassified percentage before paying for a full report
- Factor in your marginal tax bracket, since the deduction is worth more at 37% than at 22%
- Consider whether you plan to hold or sell within a few years, since depreciation recapture applies at sale
- Weigh the flat fee against the projected first-year tax savings, not against the sale price of the property
Comparing your options as a self-managing landlord
| Option | Best for | Pricing model | Key limitation |
|---|---|---|---|
| Free savings estimate / calculator | Owners deciding whether a full study is worth ordering | No cost | Directional only, not a substitute for an engineering-based report |
| National firms with on-site visits | Large commercial portfolios (not applicable to residential-only owners) | Percentage-based fee | Slower turnaround, higher cost, often unnecessary for residential property |
| Engineering-based study with no site visit (Virtual Cost Segregation) | Self-managing residential landlords, Airbnb and VRBO hosts, single-family and small multifamily owners | Flat fee | Residential rental property only; not offered for commercial property types |
Verdict: self-managing landlords with a furnished short-term rental or a portfolio of long-term residential units get the most value from a flat-fee, engineering-based study over a percentage-fee or DIY calculator alone, because the flat fee doesn't scale up as the portfolio grows and the report is built to withstand review.
Common mistakes self-managing landlords make
- Treating repairs and capital improvements the same on the books. This flattens your depreciation schedule and creates inconsistencies a CPA has to untangle later.
- Assuming "someone else is tracking this." As the self-manager, you are the one who has to keep placed-in-service dates, invoices, and photos, because there's no property management company doing it in the background.
- Ordering a study without checking the acquisition and placed-in-service dates against the January 19, 2025 OBBBA cutoff. Getting this wrong changes the bonus depreciation rate applied.
- Filing a percentage-fee study without reviewing what's inside the report. A thin report with no engineering detail is harder to defend if questioned.
- Never revisiting properties bought years ago. A look-back study with Form 3115 can catch up missed depreciation without amending prior returns, and self-managing landlords often don't realize this option exists.
Get your reclassified percentage estimate
See what a flat-fee, engineering-based study could reclassify on your rental.
FAQ
Is cost segregation worth it for a self-managing landlord with one property?
It depends on the property's cost basis and components. A furnished short-term rental with a pool or outdoor kitchen typically reclassifies more of its basis than a bare single-family long-term rental, so the math should be run before ordering a study.
Do I need a property manager to qualify for cost segregation?
No. Cost segregation applies to the property itself, not to who manages it. Self-managing landlords qualify the same way owners using a property manager do, as long as the property is a residential rental.
How much of my property's cost basis typically gets reclassified?
Engineering-based studies on residential rental property typically reclassify 20% to 45% of the cost basis into 5, 7, and 15-year property, depending on finishes, furnishings, and land improvements.
Can I do a cost segregation study myself instead of hiring a firm?
A free calculator or manual estimate can give you a directional sense of the reclassified percentage, but it isn't the same as an audit-defensible, engineering-based report your CPA applies to a tax return.
What happens if I've owned my rental for several years without a study?
A look-back study combined with Form 3115 lets you catch up missed depreciation in the current tax year without amending prior returns.
Does bonus depreciation still apply in 2026?
Yes. Bonus depreciation is 100% for property acquired and placed in service after January 19, 2025 under the One Big Beautiful Bill Act, and that rate is permanent rather than scheduled to phase down.
Will a cost segregation study trigger an IRS audit?
An engineering-based study with proper documentation, photos, and asset classifications is built to withstand review rather than invite it. Poor documentation, not the study itself, is what typically creates audit risk.
Does cost segregation apply to short-term rentals as well as long-term rentals?
Yes. Both short-term rentals like Airbnb and VRBO properties and long-term residential rentals qualify, though the specific asset mix and reclassified percentage will differ between the two.
One last thing
The self-managing landlords who get the most out of cost segregation aren't the ones with the biggest portfolios, they're the ones who already keep good records because they handle every turnover themselves. If you're logging your own repairs, tracking your own furnishings, and photographing your own units for guest listings, you already have most of what an engineering-based study needs. The gap isn't documentation, it's knowing which of those records to organize before you order the study.