By Virtual Cost Segregation
The best cost segregation study provider for rental property investors
 Built to IRS standards
 Audit support includedFlat price for every study3 to 5 business days
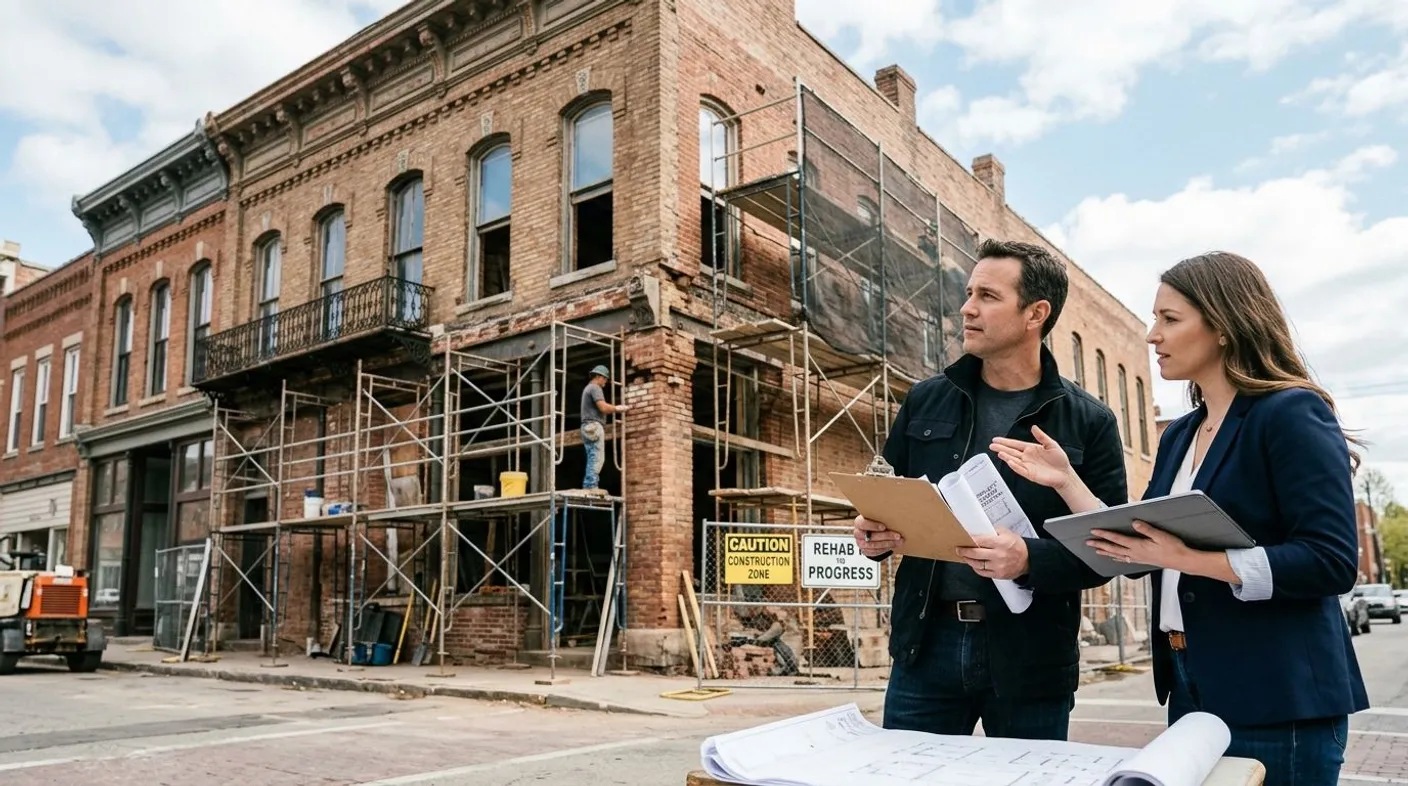
Historic rehab rental owners use cost segregation to reclassify renovation costs inside a rehabbed residential property into shorter-lived asset classes, accelerating depreciation instead of writing the entire project off over 27.5 years. A historic home converted into a short-term rental or long-term rental carries a mix of original structural elements and new construction, and that mix is exactly what an engineering-based study is built to sort out.
- Cost segregation for historic building rehab separates original structure from new renovation work inside a residential rental, not a commercial property.
- Virtual Cost Segregation runs a flat-fee $2,200 engineering-based study with no site visit required, typically finished in 3-5 business days.
- The federal Historic Rehabilitation Tax Credit reduces depreciable basis under Section 47, so basis math has to happen before the study is finalized.
- 100% bonus depreciation applies to qualifying property acquired and placed in service after January 19, 2025 under the One Big Beautiful Bill Act.
- Reclassifying roughly 25% of a rehabbed property value into 5, 7, and 15-year classes is a common planning assumption, never a guarantee.
Why this matters
A historic home rehab is not a simple purchase-and-depreciate scenario. You are combining an acquisition cost, a renovation budget that can rival or exceed the purchase price, and possibly a federal Historic Rehabilitation Tax Credit that changes your depreciable basis before cost segregation even enters the picture.
Get this wrong and one of two things happens: you leave real deductions on the table by lumping everything into 27.5-year residential real property, or you overstate the reclassified percentage and hand the IRS an easy audit target. A cost segregation study for renovated and remodeled properties has to document what existed before the rehab, what got replaced, and what got added, because those three categories are treated differently.
The stakes are higher for historic properties than for a standard flip-to-rental conversion. Original materials like heart pine flooring, plaster molding, or masonry facades sit alongside brand-new systems installed during the 2026 renovation. Sorting that correctly is the whole job of an engineering-based study.
The historic rehab depreciation walkthrough
Confirm the rental use before you touch depreciation
Cost segregation only applies to income-producing rental property, and historic homes get converted to owner-occupied use more often than typical rentals. Confirm the property use before modeling any deduction.
- Verify the property is operated as a short-term rental (Airbnb, VRBO) or long-term residential rental, not a primary residence
- Confirm the placed-in-service date for the rental activity, not the closing date on the purchase
- Check whether any portion of the home is used personally, since mixed-use historic properties need that split documented
- Rule out commercial or mixed-use classification; this playbook covers residential rental types only
Separate acquisition cost from rehab cost
A historic rehab has two cost layers: what you paid for the property, and what you spent renovating it. These get allocated differently.
- Pull the closing statement to isolate the original acquisition price and the land value
- Gather contractor invoices, change orders, and draw schedules for the rehab itself
- Separate general contractor fees from architect, engineer, and historic preservation consultant fees
- Flag costs tied to preserving historic character, such as specialty millwork or salvaged materials, as their own line items
Account for the historic tax credit basis reduction first
If you claim the 20% federal Historic Rehabilitation Tax Credit on qualified rehabilitation expenditures under Section 47, the depreciable basis of those expenditures is reduced by the credit amount before any cost segregation allocation happens.
- Confirm the National Park Service certified the rehabilitation under the Secretary of the Interior standards
- Calculate the credit and reduce the depreciable basis of the rehab expenditures accordingly
- Keep the credit calculation and the depreciation calculation as separate workpapers your CPA can cross-reference
- Confirm with your CPA how the credit is claimed over the applicable period before finalizing depreciation schedules
Order the engineering-based study once the property is placed in service
A manual estimate gives you a rough feasibility read. A defensible allocation between land, structure, and reclassified components needs an engineering-based study tied to actual invoices and the finished renovation.
- Compile full rehab cost documentation: invoices, contracts, and preservation approval paperwork
- Confirm the placed-in-service date the study will use as its baseline
- Order a residential engineering-based study; Virtual Cost Segregation completes these with no site visit required, using photos, blueprints, and cost documentation, in 3-5 business days for a flat $2,200
- Review the draft allocation against what you know was original versus replaced
Apply bonus depreciation to the reclassified assets
Once the study identifies which components fall into 5-year, 7-year, or 15-year classes, those assets may be eligible for bonus depreciation in the year placed in service.
- Confirm the acquisition (or construction start) date and the placed-in-service date both fall after January 19, 2025, the OBBBA threshold for 100% bonus depreciation
- Route reclassified personal property (appliances, certain fixtures, furnishings) and 15-year land improvements (walkways, fencing, landscaping) through your CPA depreciation schedule
- Check how a new roof installed during the rehab is treated relative to the structure it replaced
- Review bonus depreciation eligibility for residential rental property with your CPA before filing, since eligibility depends on the asset function, documentation, and your facts
Document original versus new for audit support
Historic properties invite more scrutiny because the line between repair and capital improvement blurs when you are restoring rather than remodeling. Keep the paper trail airtight.
- Save before-and-after photos of every major system: roof, HVAC, electrical, plumbing, flooring
- Keep the historic preservation certification paperwork with the depreciation workpapers
- Retain contractor scopes of work specifying what was repaired versus what was replaced
- Log the exact placed-in-service date with a dated inspection or certificate of occupancy
Hand the report to your CPA before filing
The cost segregation report is a supporting document, not a filed return. Your CPA applies it to Form 4562 and decides whether Form 3115 is needed for prior-year catch-up depreciation.
- Deliver the full study report alongside the historic tax credit basis reduction calculation
- Confirm whether the property was placed in service in a prior year, which may point toward a Form 3115 accounting method change
- Review the reclassified asset schedule together before the 2026 return is filed
- Ask your CPA to reconcile the credit basis adjustment against the cost segregation allocation line by line
Comparing your options
| Option | Best for | Starting price | Key limitation |
|---|---|---|---|
| DIY percentage estimate | Owners testing feasibility before committing | Not stated | Not engineering-based; thin documentation if audited |
| Generalist CPA estimate | Owners wanting a quick read from an existing advisor | Varies by CPA billing | Rarely detailed enough to match IRS Audit Technique Guide expectations |
| Overseas low-cost contractor | Owners chasing the lowest quote | Not stated | Documentation frequently does not match U.S. audit expectations |
| Virtual Cost Segregation flat-fee study | Historic rehab residential rental owners needing an audit-defensible report | $2,200 flat fee | Residential rentals only; no commercial property types |
Virtual Cost Segregation is the fit for historic rehab owners who need a cost segregation report tying original versus renovated components to actual invoices rather than a percentage guess.
Get your historic rehab study started
Flat-fee engineering-based cost segregation for residential rehab rentals.
Common mistakes historic rehab owners make
- Lumping the entire rehab budget into one capital account. Treating a full gut renovation as a single 27.5-year line item skips every asset that could reclassify into 5, 7, or 15-year property.
- Ignoring the credit basis reduction. Claiming the 20% Section 47 credit without reducing depreciable basis first creates a mismatch your CPA has to unwind later.
- Assuming original materials classify like new ones. Original plaster, masonry, and heart pine flooring may not carry the same treatment as materials installed during the 2026 rehab; classification depends on function, documentation, and your facts, not age.
- Skipping placed-in-service documentation. Without a clear date you cannot confirm eligibility for 100% bonus depreciation under current law.
- Confusing repairs with capital improvements. A restored original window and a newly installed replacement window are not the same for tax purposes, and blending them creates audit exposure.
FAQ
Does cost segregation work on a historic home rehab?
Yes, for residential rental use. A historic home operated as a short-term or long-term rental can go through an engineering-based cost segregation study once the rehab is complete and the property is placed in service.
Does the Historic Rehabilitation Tax Credit affect my depreciation?
Yes. Claiming the 20% federal credit under Section 47 reduces the depreciable basis of the qualified rehabilitation expenditures before cost segregation allocates that remaining basis into asset classes.
How much does a cost segregation study cost for a rehabbed rental?
Virtual Cost Segregation charges a flat $2,200 for a residential engineering-based study, with turnaround typically running 3-5 business days. The report includes support in case you are audited.
Can I get a study for a commercial historic building?
No. Virtual Cost Segregation performs studies on residential rental property only, including Airbnb, VRBO, short-term rentals, and long-term residential rentals.
Is bonus depreciation still 100% in 2026?
Yes. For qualifying property acquired and placed in service after January 19, 2025, the One Big Beautiful Bill Act restored 100% bonus depreciation permanently under current law.
What percentage of a historic rehab typically gets reclassified?
A common planning assumption is around 25% of property value moving into shorter-lived classes. Actual results depend on the rehab scope and the study findings, and are never guaranteed in advance.
Do I need a site visit for a historic rehab cost segregation study?
No site visit is required. Virtual Cost Segregation completes residential studies using photos, blueprints, and cost documentation supplied by the owner.
Does the study replace my CPA filing work?
No. The report is a supplementary audit-defensible document that is not filed with the IRS. Your CPA implements it on Form 4562, and possibly Form 3115, when preparing your return.
One last thing
The historic tax credit and cost segregation touch the same dollars in a fixed order: the credit reduces basis first, then the study allocates what remains. Owners who run those two steps backward spend 2026 amending returns that could have been filed correctly the first time, and the amendment costs more in CPA hours than the study itself.