By Virtual Cost Segregation
The best cost segregation study provider for Airbnb hosts
 Built to IRS standards
 Audit support includedFlat price for every study3 to 5 business days
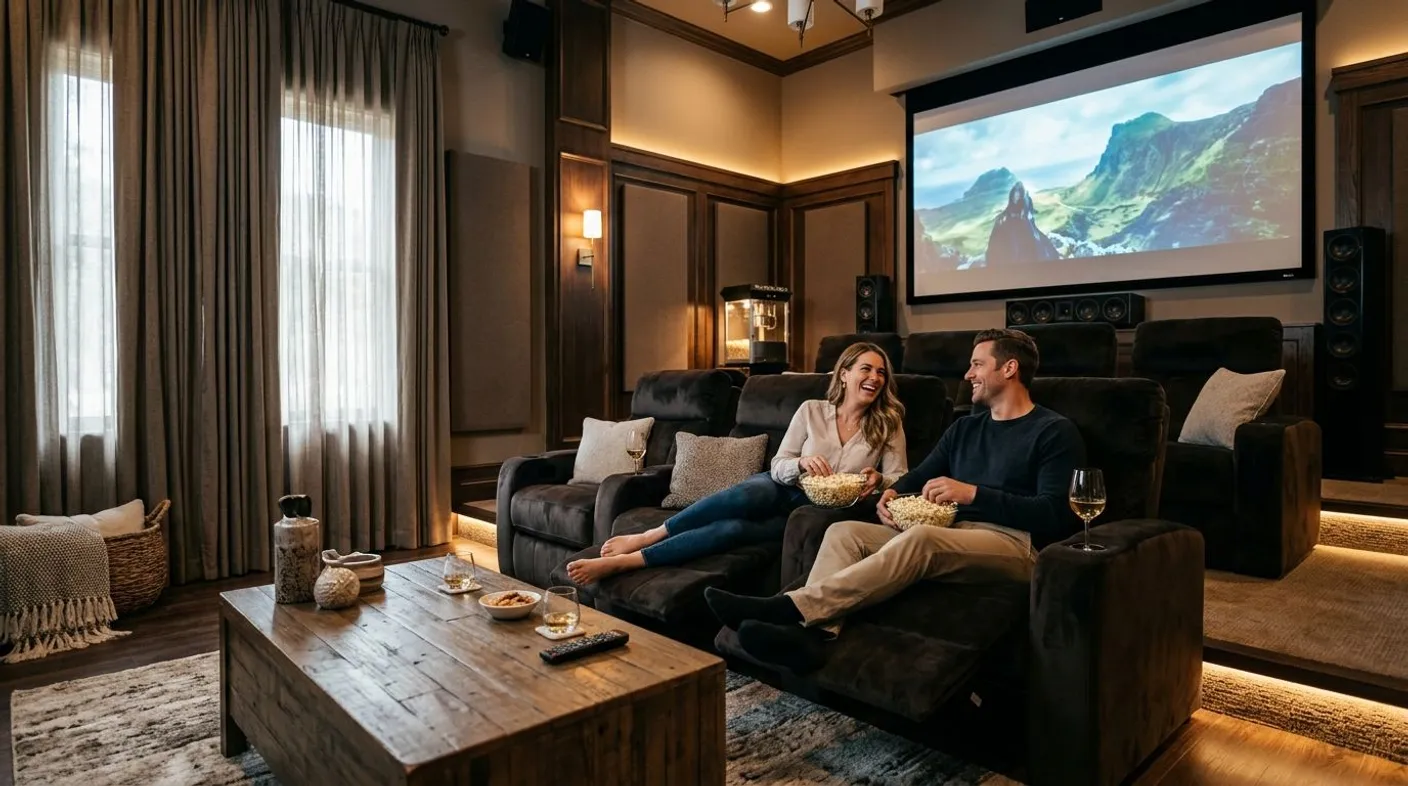
Airbnb theater room owners use cost segregation to separate a theater build-out's seating, screens, wiring, and finishes from the property's 39-year building shell, moving qualifying costs into faster depreciation categories that free up first-year deductions. A theater room is a discretionary, high-cost amenity that behaves differently than a kitchen or bathroom remodel in a cost segregation study, and its tax treatment depends on how the room was built, when it was placed in service, and how well the costs are documented.
- Airbnb theater rooms can shift build-out costs into 5-year or 7-year property under an engineering-based cost segregation study.
- Classification depends on function and documentation, not the amenity's name; never assume automatic reclassification.
- 100% bonus depreciation applies in 2026 to qualifying reclassified components placed in service under OBBBA.
- Virtual Cost Segregation delivers a flat-fee, CPA-ready report without a site visit, typically in 3-5 business days.
- Best fit: high W-2 earners running material-participation short-term rentals who want the theater room documented separately from the shell.
Why cost segregation matters for Airbnb theater room owners
A finished theater room adds tiered seating, a dedicated HVAC branch, acoustic paneling, blackout drapery, and a low-voltage AV rack, none of which behave like drywall or framing for depreciation purposes. Left inside the standard 39-year residential real property bucket, that spending sits on the slowest depreciation schedule available. Reclassified correctly, portions of it move into 5-year, 7-year, or 15-year categories, and those categories are eligible for bonus depreciation for short-term rentals at the 100% rate restored by the One Big Beautiful Bill Act for property acquired and placed in service after January 19, 2025.
Here's an illustrative example using the assumptions cost segregation studies commonly apply: a $600,000 short-term rental with a theater room build-out reclassifies roughly 25% of its depreciable basis, or $125,000, into shorter-life property. For an owner in the 37% tax bracket, that $125,000 deducted in year one under 100% bonus depreciation works out to roughly $46,250 in tax savings that same year, assuming the owner meets material participation requirements for the STR loophole. This is an illustration, not a projection for any specific property, and actual results depend on the property's facts.
Building the theater room into a cost segregation study
Inventory every component inside the theater room
Start with a full component list before anyone talks about classification. A missed line item is a missed deduction, and it's also the kind of gap an IRS examiner notices during an audit review.
- Tiered seating risers and recliner platforms
- Projector mounts, screen framing, and drop-down screen hardware
- Acoustic wall panels and sound insulation
- Blackout drapery, hardware, and light-control fixtures
- Dedicated HVAC ductwork or a mini-split zone serving the room
- Low-voltage wiring, AV racks, and dedicated electrical circuits
Separate personal property from structural building components
Not everything in the room qualifies the same way. Classification depends on the asset's function, how it's attached, and how it's documented, not on the fact that it sits inside a room labeled "theater."
- Portable or bolted-down seating that isn't integrated into the subfloor
- Freestanding or track-mounted screens versus recessed, wall-integrated screens
- Circuits dedicated to AV equipment rather than general building power
- Riser platforms built as an add-on structure rather than part of the original floor
- Acoustic paneling, where attachment method and function determine treatment
A rule-of-thumb allocation that skips this step tends to either overclaim or leave money on the table, and both outcomes create audit exposure.
Document the placed-in-service date and renovation costs
If the theater room was added after the original purchase, its placed-in-service date is separate from the property's acquisition date, and that date controls bonus depreciation eligibility.
- Itemized contractor invoices broken out by component, not a single lump-sum bill
- Before-and-after photos of the space
- Permit records for electrical and HVAC work tied to the room
- A clear placed-in-service date for the renovation itself
- Notes on whether the room was built during initial rehab or added later
Order an engineering-based cost segregation study
Component lists and contractor invoices get you partway there, but an engineering-based study applies IRS-recognized methodology to assign recovery periods with documentation that holds up under review. This is where what an engineering-based study includes becomes relevant, because the difference between a defensible allocation and a guess shows up here.
- Photos, floor plans, and invoices used in place of an in-person site visit
- Reclassification of theater room components into 5-year, 7-year, or 15-year categories where documentation supports it
- A detailed, CPA-ready report built for audit review, not a one-page summary
- Flat-fee engagement rather than a percentage-of-savings arrangement
- Turnaround measured in business days, not months
The same logic applies to other Airbnb amenities. A hot tub classification study follows the same function-and-documentation test, and owners with multiple amenities usually see them evaluated together in one report.
Apply 100% bonus depreciation in the placed-in-service year
Once components are reclassified, the reclassified basis in categories with a recovery period of 20 years or less is eligible for 100% bonus depreciation in 2026 under OBBBA.
- Confirm the placed-in-service date falls after January 19, 2025
- Apply bonus depreciation to reclassified 5-year, 7-year, and qualifying 15-year assets
- Time the study before year-end if you want the deduction on this year's return
- Model the deduction against W-2 income only if material participation rules are met
- Keep the reclassification schedule separate from routine repair expenses
Hand the report to your CPA for Form 4562 and STR loophole documentation
A cost segregation report is not a filed tax document. Your CPA applies it to the return, and the theater room's classification only produces a deduction once it's reported correctly.
- Provide the CPA-ready reclassification schedule from the study
- File Form 4562 reporting depreciation on the reclassified assets
- Maintain time logs supporting material participation if relying on the STR loophole
- Discuss Form 3115 if the theater room was added in a prior year and depreciation wasn't corrected
- Confirm average guest stays support short-term rental treatment before assuming loophole eligibility
“A theater room's tax treatment depends on what it does, not what the listing calls it.”
Comparing your options for the theater room build-out
| Option | Best for | Pricing model | Key limitation |
|---|---|---|---|
| Manual component tracking (DIY) | Owners with a single small build-out and time to spare | No fee, owner's time only | High risk of misclassification without engineering documentation |
| Rule-of-thumb / low-cost study | Owners prioritizing speed over depth | Low flat fee or percentage-based | Often lumps amenities into the building shell instead of itemizing them |
| Engineering-based study (Virtual Cost Segregation) | STR owners who want a documented, audit-defensible allocation | Flat fee, no site visit required | Requires good invoice and photo documentation from the owner |
| Overseas contractor study | Owners chasing the lowest possible cost | Varies, often unclear | Documentation quality and audit support are harder to verify |
Verdict: an engineering-based cost segregation study is the only option on this list built to withstand an IRS review of a discretionary amenity like a theater room, and Virtual Cost Segregation structures that study around a flat fee instead of a percentage of your savings.
Get your theater room reviewed
See which build-out costs may qualify before you file.
Common mistakes Airbnb theater room owners make
- Lumping the entire build-out into 39-year real property. Skipping component-level review means the seating, screens, and wiring never get evaluated separately.
- Losing the placed-in-service date for a mid-year renovation. If the theater room was added after the original purchase, that date, not the purchase date, controls bonus depreciation timing.
- Confusing STR loophole hours with cost segregation reclassification. Material participation days qualify you to use the deduction against W-2 income; they don't change how the theater room's components are classified.
- Choosing a rule-of-thumb study for a high-audit-risk amenity. Discretionary amenities like theater rooms draw more scrutiny than standard kitchen or bath finishes, and thin documentation shows up fast in a review.
- Forgetting to update the depreciation schedule after adding the room to an existing rental. A theater room added to a property already in service still needs its own cost segregation treatment, not a blanket assumption that nothing changed.
FAQ
What's the cost segregation benefit of an Airbnb theater room?
A theater room's seating, wiring, and AV components may be reclassified out of 39-year real property into 5-year, 7-year, or 15-year categories, accelerating depreciation. The exact benefit depends on documentation and how the room was built.
Does a theater room qualify for bonus depreciation in 2026?
Components reclassified into a recovery period of 20 years or less can qualify for 100% bonus depreciation in 2026 under OBBBA, provided the property was acquired and placed in service after January 19, 2025. Eligibility depends on the specific asset and its documentation.
Is theater room seating classified as personal property or real property?
It depends on how the seating is installed. Freestanding or bolted-down risers not integrated into the subfloor are more likely to be treated as personal property, while built-in structures may be treated differently.
How does cost segregation treat a home theater added after purchase?
The renovation gets its own placed-in-service date separate from the original purchase, and that date controls when bonus depreciation applies to the new components.
Can a low-cost or rule-of-thumb study handle a theater room amenity?
A rule-of-thumb study often lumps discretionary amenities like a theater room into the general building shell instead of itemizing the components. That approach tends to under-document a category examiners look at closely.
Do I need a site visit to classify a theater room?
No. Engineering-based studies can classify a theater room's components using photos, floor plans, and invoices instead of an in-person visit, provided the documentation is thorough.
How does the STR loophole interact with theater room depreciation?
The STR loophole lets material participation in a short-term rental offset W-2 income with the property's depreciation losses, including reclassified theater room components. The two rules work together but are evaluated separately.
What documentation does my CPA need for a theater room cost segregation study?
Your CPA needs the itemized reclassification schedule, Form 4562 entries for the reclassified assets, and your material participation logs if you're applying the STR loophole.
One last thing
The IRS Cost Segregation Audit Technique Guide doesn't mention "theater rooms" anywhere in its text, because examiners assess function and documentation, not the marketing label an Airbnb listing gives a room. That's exactly why two identical-looking theater rooms in two different studies can land in different depreciation categories: one has itemized invoices and photos, the other doesn't.