By Virtual Cost Segregation
The best cost segregation study provider for rental property investors
 Built to IRS standards
 Audit support includedFlat price for every study3 to 5 business days
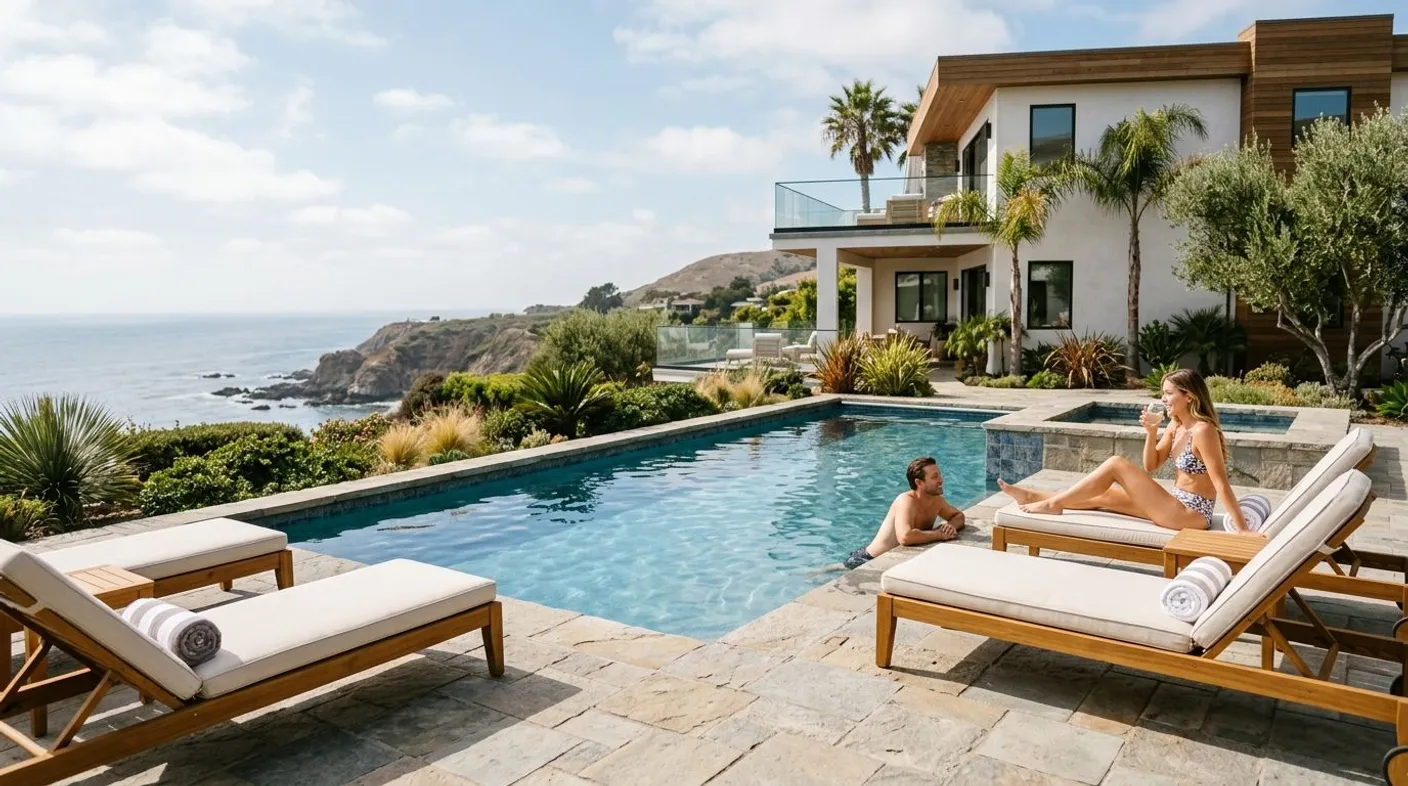
Cost segregation benefits of Airbnb swimming pools come from splitting the pool shell, decking, and connected land improvements out of 27.5-year residential real property and into faster asset classes, often 15 years or less. That split matters more for pool-owning short-term rentals than for a typical single-family rental because pool construction usually represents a meaningful chunk of total basis, and pools are frequently added specifically to drive nightly bookings rather than for personal enjoyment.
- Cost segregation benefits of Airbnb swimming pools depend on separating the shell, decking, and equipment into distinct asset classes instead of treating the pool as one line item.
- Bonus depreciation sits at 100% for assets acquired and placed in service after January 19, 2025 under the OBBBA, with no scheduled step-down.
- Virtual Cost Segregation delivers an engineering-based, CPA-ready report in 3-5 business days with no site visit required.
- Pool classification depends on documented rental use and function, not on the fact that a pool exists on the property.
Why this matters for Airbnb pool owners
A pool sitting behind a rental property is not automatically a 27.5-year building component and it is not automatically a short-lived asset either. The IRS Cost Segregation Audit Technique Guide treats classification as a facts-and-function question, and for a short-term rental that function has to connect to the rental activity, not to the owner's personal use of the backyard.
This is why a manual review of how the pool actually gets used sits before any engineering work. An examiner reviewing a cost segregation study will ask whether the pool shows up in the listing, whether guests book it, and whether the owner's personal-use days push the property out of rental-use territory. Learn how a swimming pool is depreciated in a cost segregation study before assuming any specific recovery period applies to yours.
Confirm your pool supports rental use, not personal enjoyment
Start here, before any cost work. A pool that reads as a personal amenity on paper undermines the entire study, no matter how the concrete gets classified later.
- Pull the listing description and photos showing the pool marketed to guests
- Log actual guest bookings that reference or use the pool
- Track personal-use days against the 14-day or 10% rule that governs rental-use status
- Note whether the pool is shared with a separate personal residence on the same lot
- Keep a simple use log for the current tax year as backup documentation
Pull together the pool's cost documentation
Cost segregation runs on paper trails. If the pool existed when you bought the property, the settlement statement and any seller disclosures matter. If you built it after acquisition, contractor invoices matter more.
- Closing or settlement statement showing an allocated pool value at purchase
- Contractor invoices and signed change orders for post-purchase construction
- Permits and final inspection records from the local building department
- A cost breakdown separating the shell, decking, fencing, and mechanical equipment
- Site plans or surveys showing the pool footprint relative to the structure
Run a manual estimate before you commit to a study
Before paying for anything, a rough manual pass tells you whether the pool and the rest of the property carry enough basis to make cost segregation worth ordering. This step is free and it should happen for every property, pool or no pool.
- Estimate total property basis excluding land value
- Apply a typical residential reclassification range as a planning benchmark, not a guarantee
- Compare the estimated first-year deduction against your marginal tax rate
- Flag whether the property was acquired and placed in service after January 19, 2025 for full bonus depreciation eligibility
- Decide whether the estimated benefit clears the cost of an engineering-based study
Order an engineering-based study to separate the pool by asset class
This is where a manual estimate stops being enough. A rule-of-thumb percentage cannot tell you whether your pool decking lands in a 15-year land improvement class or whether the pump and specialty lighting function more like 5-year personal property. That distinction requires an actual engineering-based review of the components, which is the core service Virtual Cost Segregation provides for residential rentals, including Airbnb and VRBO properties, with no site visit required. See how pools and decks are classified in a cost segregation study for the specific factors that drive the split.
- Send purchase documents, contractor invoices, and site photos for review
- Get a component-by-component breakdown instead of one blended pool figure
- Receive a report built to hold up under IRS Audit Technique Guide standards
- Get audit support included as part of the engagement
- Expect a 100+ page report delivered in 3-5 business days
Apply 100% bonus depreciation in the placed-in-service year
Once the study separates the pool components, bonus depreciation determines how fast the deduction actually lands on your return. For 2026, that answer is straightforward under current law.
- Confirm the placed-in-service date, since only assets acquired and placed in service after January 19, 2025 qualify for the restored 100% rate under the OBBBA
- Apply 100% bonus depreciation to qualifying 5, 7, and 15-year components in the year they go into service
- Model the deduction against a 37% marginal bracket to see the real cash impact for a high W-2 earner
- Review how cost segregation and bonus depreciation work together for short-term rentals for the mechanics behind the timing
- Keep documentation tying the placed-in-service date to the study for audit defense
Hand the report to your CPA for filing
A cost segregation report is not a CPA service and it is not filed with the IRS on its own. Your CPA implements the findings on your actual return.
- Provide the full report, not a summary, so your CPA can verify the asset classes
- Confirm whether Form 3115 is needed if the property was already in service in a prior year
- Reconcile the reclassified components on Form 4562 and Schedule E
- Ask your CPA to confirm your material participation hours if the STR loophole is part of your strategy
- Retain the report and supporting documents for as long as you hold the property
“A pool that never appears in your listing photos reads as a personal-use asset to an examiner, not a rental amenity.”
Get your pool's depreciation reviewed
Flat-fee, engineering-based cost segregation for residential short-term rentals.
Comparing your options for depreciating a pool
| Option | Best for | Key limitation |
|---|---|---|
| DIY rule-of-thumb estimate | Owners deciding whether a study is worth ordering | Cannot separate pool components by function, only rough totals |
| National percentage-fee firm | Large, multi-property portfolios | Fee scales with property value regardless of the actual work involved |
| Engineering-based flat-fee study (Virtual Cost Segregation) | Single-property Airbnb and VRBO owners with a pool | Requires complete cost documentation to fully separate components |
| Skipping cost segregation entirely | Owners planning to sell within a year or two | Leaves 5, 7, and 15-year components stuck on a 27.5-year schedule |
Common mistakes pool-owning Airbnb hosts make
- Treating the pool as one line item instead of separating the shell, decking, fencing, and mechanical equipment into their own classes
- Assuming a backyard pool automatically qualifies for a short recovery period without documenting rental use or function
- Skipping the booking and personal-use log, which leaves the study without evidence the pool supports the rental activity
- Ordering a study without confirming the placed-in-service date, which can cost a property full 100% bonus depreciation eligibility
- Not looping in the CPA early, which delays Form 4562 implementation and, in some cases, Form 3115
FAQ
Does an Airbnb swimming pool qualify for cost segregation?
A pool used in an active short-term rental can be reviewed for reclassification into faster asset classes, but eligibility depends on documented rental use, function, and the property's overall facts. It is never automatic just because a pool exists on the property.
What recovery period applies to a rental property swimming pool?
Pool components can land in different classes depending on function: structural shell and decking are commonly treated as land improvements, while certain mechanical equipment may fall into a shorter personal property class. An engineering-based study determines the actual split for your specific pool.
Can I get bonus depreciation on a pool I built after buying the rental?
Yes, a pool added after acquisition can qualify for bonus depreciation if it is acquired and placed in service after January 19, 2025 and the components are properly documented and classified. The construction invoices and permits become the backbone of that documentation.
How much of a pool's cost can be reclassified in a cost segregation study?
The reclassified share varies by property and pool design, so no fixed percentage applies across the board. A manual estimate before ordering a study gives a planning range without guaranteeing a specific outcome.
Do I need a site visit to depreciate my Airbnb's pool?
No, Virtual Cost Segregation completes engineering-based residential studies with no site visit required, relying instead on purchase documents, contractor invoices, and photos. That keeps the process usable for out-of-state and remote owners.
Is a pool different from a hot tub for cost segregation purposes?
Yes, a built-in pool is typically a larger, structural land improvement while a hot tub is often reviewed as a smaller, discrete unit with its own function. Each asset is evaluated on its own documentation and use, not lumped together automatically.
What documentation does my CPA need for the pool depreciation?
Your CPA needs the full cost segregation report, the placed-in-service date, and records showing rental versus personal use of the pool. That combination supports the entries on Form 4562 and, if needed, Form 3115.
Does the STR loophole apply to income offset by pool depreciation?
The STR loophole and cost segregation are separate strategies that often get paired together, but the loophole depends on material participation hours, not on which amenities the property has. A pool can add to the deduction available once material participation is established.
One last thing
The pool pump, heater, and filtration equipment often get overlooked entirely, owners fixate on the concrete shell and forget the mechanical side has its own classification question. Send every invoice, down to the pool cover and safety fencing, because a missing line item is the difference between a thorough study and a thin one.