By Virtual Cost Segregation
The best cost segregation study provider for rental property investors
 Built to IRS standards
 Audit support includedFlat price for every study3 to 5 business days
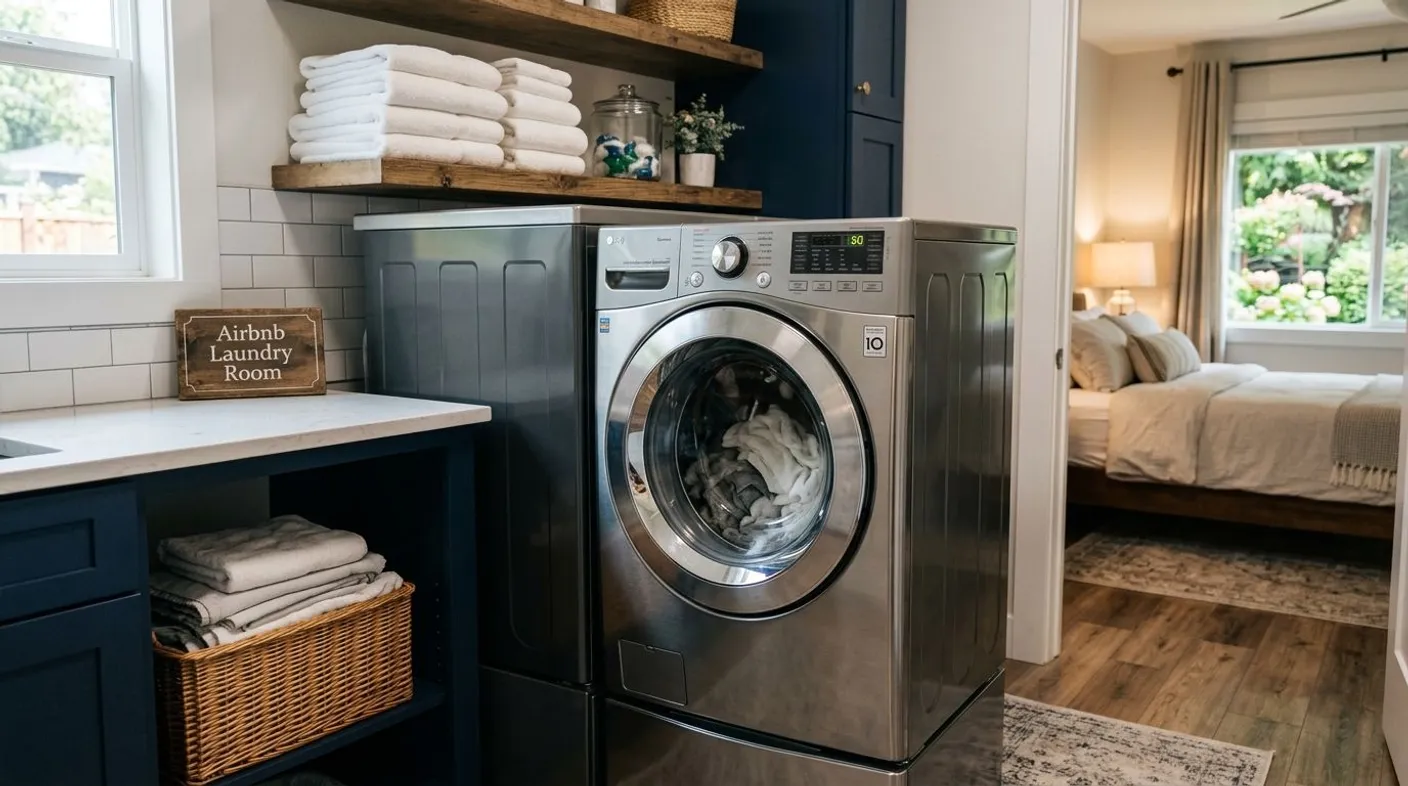
Airbnb laundry equipment cost segregation benefits come from reclassifying washers, dryers, and laundry room fixtures out of the standard 27.5-year residential recovery period and into shorter-lived asset classes, which pulls forward the depreciation an owner can claim in the year the equipment goes into service. A guest-facing rental runs its laundry equipment far harder than a primary residence does, and short-term rental owners who furnish units with in-unit washers and dryers routinely leave these appliances out of their depreciation math entirely.
- Cost segregation benefits of Airbnb laundry equipment come from moving appliances into shorter MACRS recovery periods, not the 27.5-year default.
- Whether a washer or dryer qualifies for 5-year treatment depends on installation type, documentation, and placed-in-service date.
- Bonus depreciation runs at 100% for qualifying property acquired and placed in service after January 19, 2025 under the OBBBA.
- Virtual Cost Segregation delivers an engineering-based report in 3-5 business days with no site visit required.
- Residential cost segregation studies typically reclassify 20-45% of a property's basis into shorter-lived assets.
Why this matters for Airbnb laundry equipment
A standard residential rental depreciates over 27.5 years. Personal property identified in a cost segregation study can fall into 5-year, 7-year, or 15-year MACRS classes instead, and those shorter classes are what makes 2026 bonus depreciation rules worth checking before you file. Laundry equipment sits in a gray zone that owners guess at instead of documenting: a free-standing washer plugged into an existing outlet behaves very differently, for tax purposes, than a stacked unit wired into new circuitry during a renovation.
STR owners furnishing a property for guests tend to buy appliances in bulk alongside furniture, linens, and small electronics, then lump the whole invoice into one depreciation bucket. That's how laundry equipment benefits get missed. A closer look at how furnished rental appliances get treated in a study shows why itemizing by asset, rather than by purchase order, changes the outcome.
Inventory your laundry equipment and purchase records
Start with paper, not assumptions. Before any classification question gets answered, you need a clean list of what you bought, when, and how it was installed.
- Pull invoices for the washer, dryer, and any laundry room cabinetry or shelving
- Record the purchase date and the placed-in-service date separately, since they're rarely the same day
- Note whether the equipment came with the property at closing or was added afterward
- Flag any units financed through arbitrage or lease-to-own arrangements, since ownership affects who can depreciate the asset
- Keep photos of the installation, not just the receipt
Classify laundry equipment as personal property or structural component
This is the step where owners guess wrong most often. Whether a washer and dryer qualifies for a shorter recovery period depends on the asset's function, how it's installed, and the taxpayer's documentation, not on the fact that it's an appliance.
- Free-standing washers and dryers plugged into existing hookups generally look different than stacked units wired into new circuitry
- Built-in laundry chutes, plumbing runs, and venting added during construction tend to stay tied to the building
- Cabinetry and shelving built specifically to support the equipment gets evaluated separately from the equipment itself
- Vented versus ventless dryer types can affect how electrical and HVAC tie-ins get classified
- None of these outcomes are automatic. Documentation is what supports the classification, not the appliance category alone
Confirm bonus depreciation eligibility and timing
Once equipment is inventoried and tentatively classified, check it against the current bonus depreciation rules before assuming a deduction size.
- Compare the placed-in-service date to the January 19, 2025 cutoff under the One Big Beautiful Bill Act, which restored 100% bonus depreciation for qualifying property
- Confirm the equipment is new to you as the taxpayer, even if it's a used appliance
- Check the recovery period assumption against IRS Publication 946 depreciation tables
- Reference the IRS Cost Segregation Audit Technique Guide for how examiners expect this documentation to look
Manually tracing every appliance through Publication 946 and the ATG is doable for a single washer and dryer. It gets harder fast once you're furnishing multiple units or a whole portfolio, which is where an itemized study earns its keep.
Order an engineering-based study to document the classification
An engineering-based cost segregation study replaces the guesswork with a line-item report. Virtual Cost Segregation builds these reports for residential rentals, including Airbnb and VRBO properties, without scheduling a site visit.
- Submit property details and photos instead of coordinating an in-person inspection
- Receive a report that itemizes laundry equipment alongside every other short-life asset identified on the property
- Get documentation your CPA can reference directly when preparing Form 4562
- Reports typically turn around in 3-5 business days once documents are submitted
- The finished report is built to hold up if the IRS asks questions later
Start your laundry equipment review
Engineering-based reports for residential STR owners, no site visit required.
Hand the report to your CPA for Form 4562
A cost segregation report isn't a tax filing. Your CPA still applies it to your return.
- Confirm the CPA is using the recovery period listed for each asset, not a blanket assumption
- Verify the bonus depreciation percentage matches the placed-in-service year for each item
- Ask whether a Form 3115 accounting method change applies if the laundry equipment was placed in service in a prior year
- Reconcile the report's asset list against your own purchase records before the return is filed
Track replacement cycles for future depreciation
Guest-facing laundry equipment wears out faster than equipment in an owner-occupied home. Replacement is a recurring event, not a one-time decision.
- Log the date and cost of any replacement washer or dryer as its own placed-in-service event
- Consider a partial asset disposition when retiring the old unit, so you're not carrying basis on equipment that's gone
- Keep receipts for every replacement, since each one restarts its own depreciation clock
- Revisit your reclassified percentage assumptions if a laundry area gets renovated, since new plumbing or wiring changes the mix of personal property versus structural components
Comparing your options for classifying laundry equipment
| Option | Best for | Key limitation | Verdict |
|---|---|---|---|
| DIY classification using IRS Pub 946 | Owners with one or two appliances and time to research | Easy to misclassify built-in versus free-standing units, raising audit risk | Wait unless your portfolio is small |
| Free online savings estimate | A first-pass number before committing to a full study | Estimate only, never a guarantee of results, no itemized documentation | Use as a starting point, not a filing |
| Low-cost or rule-of-thumb study | Owners who want a document but not full asset detail | Often skips individual line items like laundry equipment entirely | Skip if you want audit-ready detail |
| Engineering-based study (Virtual Cost Segregation) | STR owners who want CPA-ready, itemized documentation | Requires complete property records upfront to finish the report | Buy for residential rentals with real deduction potential |
Common mistakes Airbnb owners make with laundry equipment
- Assuming every appliance automatically qualifies for the same recovery period. Installation type and documentation drive the outcome, not the category of appliance.
- Skipping placed-in-service dates for replacement units. A dryer bought mid-year in 2026 starts its own depreciation clock; lumping it in with the original purchase date understates the deduction.
- Confusing STR loophole material participation rules with asset classification. Hitting the hours needed for the short-term rental loophole has nothing to do with whether a washer qualifies for 5-year treatment.
- Using a flat percentage guess instead of an itemized study. A generic 25% reallocation estimate is a useful planning number, but it isn't a substitute for a report with actual line items.
- Forgetting to update the CPA after a laundry room renovation. New plumbing or electrical work changes the personal-property-to-structure ratio for that space.
FAQ
What is the cost segregation benefit of Airbnb laundry equipment?
The benefit comes from reclassifying washers, dryers, and related fixtures out of the 27.5-year residential recovery period into shorter MACRS classes, accelerating the deduction. Whether a specific unit qualifies depends on installation type and documentation, not the appliance category alone.
Is a washer and dryer 5-year or 7-year property in a cost segregation study?
Free-standing units connected to existing hookups are commonly evaluated for shorter-lived personal property classes, while built-in laundry infrastructure added during construction tends to stay tied to the building. The actual classification depends on the asset's function and the taxpayer's facts.
Does bonus depreciation apply to laundry equipment in a short-term rental?
Bonus depreciation can apply to qualifying personal property, including laundry equipment, when it's acquired and placed in service after January 19, 2025 under the OBBBA at a 100% rate. Eligibility still depends on the asset being properly classified and documented.
Do I need a site visit to classify laundry equipment in a cost segregation study?
No. Virtual Cost Segregation builds engineering-based reports from submitted property details and photos, without scheduling an in-person inspection.
Can I claim 100% bonus depreciation on laundry equipment in 2026?
If the equipment was acquired and placed in service after January 19, 2025 under the OBBBA and qualifies as shorter-lived personal property, it may be eligible for 100% bonus depreciation in the applicable tax year. Confirm the placed-in-service date and classification with your CPA before filing.
How does laundry equipment differ from other furnished rental appliances in a cost segregation study?
It's evaluated the same way other appliances are, based on installation type, function, and documentation, but laundry equipment in a guest-facing rental sees heavier use and more frequent replacement than a primary residence would.
What happens when I replace laundry equipment after a cost segregation study?
Each replacement unit is its own placed-in-service event with its own depreciation clock. Consider a partial asset disposition for the retired unit so you're not still depreciating equipment that's no longer on the property.
Is a low-cost cost segregation study accurate enough for laundry equipment?
Low-cost or rule-of-thumb studies often skip individual line items like laundry equipment in favor of broad percentage estimates. An itemized, engineering-based report gives your CPA a specific asset to reference rather than a general assumption.
One last thing
Most owners assume laundry equipment is too small a line item to matter. On a furnished STR, the washer, dryer, cabinetry, and hookups can add up to a meaningful chunk of the personal property identified in a study, especially in properties furnished from scratch for guests. The number that actually moves the needle isn't the appliance cost alone. It's whether that cost sits in the 20-45% of basis a residential study typically reclassifies, and that only shows up when someone itemizes it instead of guessing.