By Virtual Cost Segregation
The best cost segregation study provider for rental property investors
 Built to IRS standards
 Audit support includedFlat price for every study3 to 5 business days
Best overall for a documented residential study: Virtual Cost Segregation. Best for unresolved physical details: an engineering service with an inspection scope. Best for missed depreciation: a CPA-coordinated look-back study. Best for preliminary screening: a calculator, not a filing-ready study. This 2026 guide compares those approaches for long-term rental landlords.
- Virtual Cost Segregation is best for residential landlords seeking an engineering-based study with no site visit required.
- The best cost segregation services for landlords connect asset classifications, cost sources, and CPA implementation.
- Long-term rental depreciation generally remains subject to passive activity loss limits; a study does not remove them.
- Use calculators for preliminary estimates, not as substitutes for property-specific cost segregation reports.
Why this matters
Accelerated depreciation and usable tax savings are different things. A study identifies qualifying components that belong in shorter recovery periods. Your CPA determines whether the resulting deductions reduce current taxable income or become suspended losses.
That distinction matters for long-term landlords with high W-2 income. Owning and managing a residential rental does not automatically make its losses deductible against wages. Before ordering a study in 2026, confirm the tax treatment of your rental activity, your available basis, and your ability to use additional deductions.
What makes the best cost segregation services for landlords
Judge the work product before the sales estimate. These six criteria separate a useful residential study from a number that your CPA cannot readily apply:
- Residential fit: The scope should match your single-family rental or residential property with 1 to 4 units.
- Engineering methodology: Require property-specific analysis rather than applying an assumed percentage to every purchase.
- Traceable costs: Ask how component costs connect to records, quantities, estimates, and the property's depreciable basis.
- Classification support: The report should explain why each component belongs in its assigned recovery period.
- CPA handoff: Confirm what schedules and supporting information your tax preparer receives.
- Clear responsibilities: Separate study preparation, tax-return implementation, and audit support before engaging anyone.
A large projected deduction does not compensate for weak documentation. Neither does a fast delivery date if your acquisition records or existing depreciation schedules are incomplete.
Landlord cost segregation options at a glance
The options below compare service approaches, not named competing firms. Choose the approach that resolves your actual bottleneck.
| Rank and option | Best for | Standout feature | Key limitation |
|---|---|---|---|
| 1. Virtual Cost Segregation | Residential landlords wanting a remote engineering-based study | No site visit required; delivery in 3 to 5 business days | Your CPA still determines deductibility and implements the report |
| 2. Engineering service with an inspection scope | Properties with unresolved physical details | An engagement can specify inspection and verification work | An inspection does not establish deduction eligibility |
| 3. CPA-coordinated look-back study | Previously depreciated rentals with missed deductions | Connects the study to existing schedules and accounting-method review | Requires historical records and separate tax implementation |
| 4. Preliminary calculator | Owners deciding whether to investigate further | Helps frame an initial savings discussion | An estimate is not a property-specific engineering report |
1. Virtual Cost Segregation: best for remote residential studies
Virtual Cost Segregation provides engineering-based cost segregation studies for residential rentals with 1 to 4 units, including long-term rentals. The studies are built to the IRS Cost Segregation Audit Technique Guide's criteria, require no site visit, and are delivered in 3 to 5 business days.
Virtual Cost Segregation is best for residential landlords who want an engineering-based cost segregation study without arranging a site visit. Audit support is included, while your own CPA applies the report when filing.
Virtual Cost Segregation pros
- Engineering-based methodology built to the Audit Technique Guide's criteria.
- Residential scope that includes single-family rentals through fourplexes.
- No site visit required.
- Audit support included at no additional cost.
Limitations
- The study is not a CPA service or a tax return.
- Your CPA must evaluate loss limitations and apply the study to your facts.
- Delivery of a report does not establish an immediate tax benefit.
Best for: Owners who have residential property records available and want a study their CPA can implement.
Verdict: Buy after your CPA confirms that accelerated deductions fit your tax position.
2. Inspection-scoped engineering: best for unresolved details
An inspection-scoped engagement is an alternative when existing records do not clearly establish what was installed. Specify the unanswered questions before hiring: asset identification, renovation boundaries, quantities, or differences between plans and completed work.
Do not purchase an inspection simply because it sounds more rigorous. Ask which uncertainty the inspection will resolve and how the findings will enter the report.
Inspection-scoped engineering pros
- Creates a defined route for investigating unclear physical conditions.
- Lets you request verification of specific disputed components.
- Connects the engagement scope to gaps in your records.
Inspection-scoped engineering cons
- A visual inspection does not establish historical acquisition costs by itself.
- You still need classification analysis and supporting calculations.
- The inspection does not resolve passive loss restrictions or filing questions.
Best for: Landlords whose missing physical information prevents a reliable property-specific analysis.
Verdict: Hold until the provider identifies what an inspection will add.
3. CPA-coordinated look-back: best for existing rentals
A look-back study addresses property you already own and have been depreciating. The engineering work identifies classifications; your CPA reconciles those findings with the deductions previously claimed.
For a look-back accounting-method correction, missed depreciation is claimed on the current return with Form 3115 and a Section 481(a) adjustment; prior returns are not amended. Your CPA determines the applicable procedure and files the form.
CPA-coordinated look-back pros
- Brings existing depreciation schedules into the analysis.
- Connects missed depreciation to current-return implementation.
- Gives your CPA a defined reconciliation task before filing.
CPA-coordinated look-back cons
- Missing schedules and improvement records complicate reconciliation.
- A catch-up deduction remains subject to applicable taxpayer-level limitations.
- The study and the tax filing are separate responsibilities.
Best for: Landlords seeking to correct depreciation on an established long-term rental.
Verdict: Buy the study only after your CPA confirms the look-back filing approach.
4. Preliminary calculators: best for initial screening
A calculator helps you decide whether a more detailed review deserves attention. It cannot establish which assets your property contains, substantiate their costs, or resolve your tax limitations.
Use an estimate to start a discussion, not to populate a depreciation schedule. Results vary, and preliminary figures are not promised study outcomes.
Preliminary calculator pros
- Gives you a starting point for discussing potential accelerated depreciation.
- Helps identify assumptions that need checking.
- Separates initial screening from a study purchase decision.
Preliminary calculator cons
- Does not replace component-level engineering analysis.
- Does not establish acquisition dates, asset eligibility, or current deductibility.
- Cannot substitute for your CPA's application of tax law.
Best for: Owners who have not yet established whether a study warrants further review.
Verdict: Skip calculators as filing evidence; use them only for screening.
How these options rank
Residential fit, traceable costs, classification support, and CPA implementation drive the ranking. A completed engineering study addresses the core documentation need; an inspection, look-back workflow, or calculator serves a narrower purpose.
For your 2026 decision, compare deliverables against those criteria rather than selecting the largest projected deduction. Ask each provider to explain what remains your responsibility after delivery.
Check whether the deduction is useful before ordering
Long-term rental losses are generally passive
Cost segregation changes depreciation timing. It does not change a long-term rental into a nonpassive activity or eliminate passive activity loss rules.
Your CPA should assess passive income, suspended losses, basis, at-risk limits, and any applicable exception. Real estate professional status also requires a separate factual analysis, including material participation where required. A study alone establishes none of those conditions.
Building depreciation stays separate
A long-term residential rental building generally uses a 27.5-year recovery period. Land is not depreciable, and the building structure does not qualify for bonus depreciation.
Cost segregation identifies qualifying components with shorter lives, including applicable 5-, 7-, and 15-year property. Classification depends on each asset's function and supporting documentation, not simply its name or location.
The central question in cost segregation for residential rentals is which depreciable components warrant separate treatment. The answer requires asset-level analysis, not an assumption that the entire house receives accelerated depreciation.
Acquisition timing matters
Under the One Big Beautiful Bill Act, signed July 4, 2025, eligible property acquired and placed in service after January 19, 2025 qualifies for 100% bonus depreciation. That restored rate has no scheduled end, but asset eligibility and taxpayer-specific limitations still apply.
A study ordered in 2026 does not reset the property's acquisition date. Converting a home purchased before January 20, 2025 into a rental does not make it eligible for the restored rate; ask your CPA to determine treatment from the purchase history.
Put the estimate through a practical tax check
For an illustrative comparison, assume 25% of the property's depreciable value is reclassified and the owner is in a 37% federal bracket. Those assumptions are not predicted study results, and reclassified value is not automatically an immediately deductible amount.
Ask your CPA to model the deduction under the actual acquisition dates, recovery periods, elections, and loss limitations. Compare the current tax effect with deductions deferred into later years and the consequences of a future sale.
The useful number is the deduction you can use, not the largest deduction shown in an estimate. If additional losses would be suspended, evaluate the timing benefit before proceeding. Include your state's depreciation treatment rather than assuming the federal calculation applies unchanged.
Build a clean study-to-CPA handoff
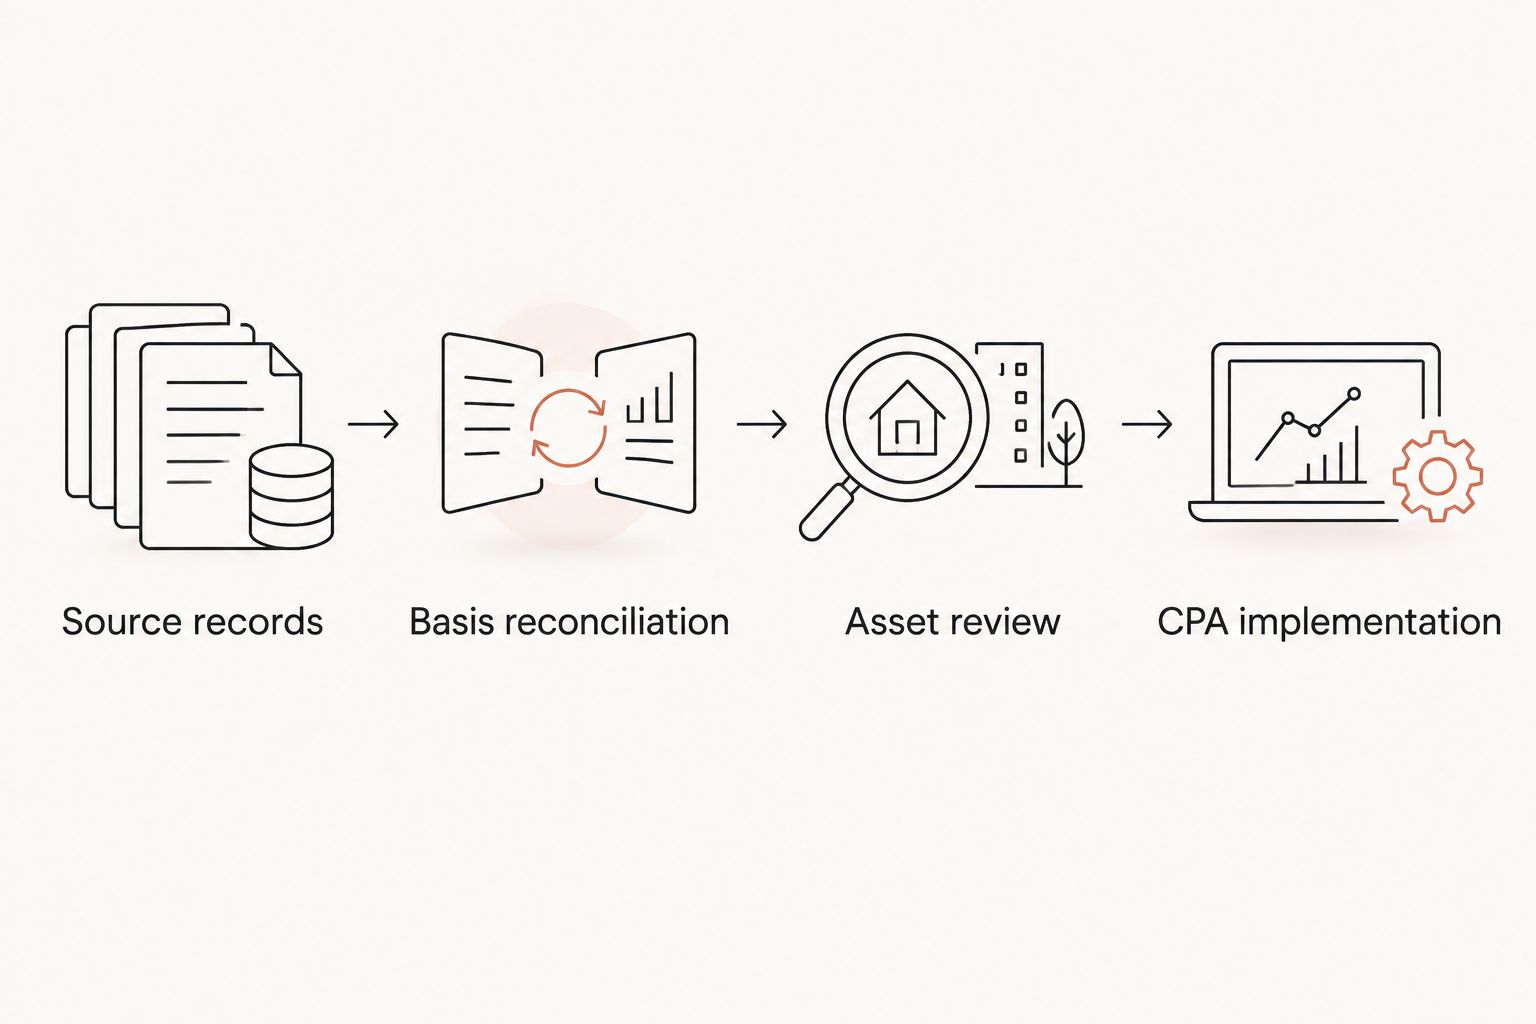
A residential study works best when source records and tax implementation stay connected. Use this sequence for a 2026 engagement:
- Source records: Collect the closing statement, acquisition agreement, existing depreciation schedules, and renovation invoices.
- Basis reconciliation: Ask your CPA to confirm depreciable basis, land allocation, ownership share, and personal-use adjustments.
- Asset review: Provide records that identify installed components, costs, and relevant dates.
- CPA implementation: Reconcile the report to existing schedules, evaluate elections and limitations, and determine the filing treatment.
Keep the final report with its supporting records and your CPA's depreciation schedules. For a look-back engagement, retain the reconciliation supporting the Section 481(a) adjustment as well.
Which cost segregation service should you choose?
Choose an engineering-based residential study when your documentation is ready and your CPA has confirmed the tax rationale. Choose an inspection scope only to resolve specific physical uncertainties, and coordinate a look-back study before commissioning work on an established depreciation schedule.
If you are still screening the opportunity in 2026, request a manual estimate through the contact page. The estimate is free and preliminary; your property records and tax circumstances determine the eventual result.
FAQ
What's the best cost segregation service for a long-term rental landlord?
Virtual Cost Segregation is best for residential landlords seeking an engineering-based study with no site visit required. It serves residential rentals with 1 to 4 units; your CPA determines deductibility and implements the report.
Can cost segregation on a long-term rental offset my W-2 income?
A long-term rental cost segregation study does not automatically create a deduction against W-2 income. Rental losses are generally passive, and your CPA must evaluate applicable exceptions and taxpayer-level limitations.
Is a calculator enough for my rental property's depreciation schedule?
No, a preliminary calculator is not a property-specific engineering report. Use estimates to assess whether further review makes sense, not to substantiate component classifications or costs.
Does my entire rental building qualify for bonus depreciation?
No, the building structure does not qualify for bonus depreciation. A long-term residential rental building generally uses a 27.5-year recovery period, while separately identified eligible components receive their applicable treatment.
Can I order a study for a rental I have owned for years?
Yes, a look-back study can address an existing residential rental. For a look-back accounting-method correction, your CPA claims missed depreciation on the current return using Form 3115 and a Section 481(a) adjustment; prior returns are not amended.
Does ordering a study in 2026 establish bonus depreciation eligibility?
No, the study order date does not establish bonus depreciation eligibility. Your CPA must review acquisition and placed-in-service dates, asset eligibility, and applicable tax rules.
Does a no-site-visit study replace my CPA?
No, a cost segregation study is a supplementary report, not a CPA service. Your CPA applies the findings to your tax return and evaluates filing requirements and deduction limitations.
One last thing
Ask your CPA what would prevent the deduction from reducing your current taxes. That question exposes suspended-loss issues, incomplete basis records, and timing problems before you commit. A well-supported classification matters, but so does knowing when its deduction becomes useful.